Budget Reforecasting: How to Update Your Budget Each Month

Budget reforecasting means updating your budget with what actually happened, then adjusting the months ahead so the numbers match your real life. You compare planned and actual income and spending, find what drifted, and rewrite next month’s plan. It takes about 30 minutes a month, and it is the difference between a budget that works and one you abandon by February.

This guide is for you if you are a salaried employee, a student or a young professional, or if you split dining, trips and events with friends. You do not need finance training. You need your bank activity, a few categories and a routine.

Valapoint
Bring More Clarity to Your Monthly Budget
Vala highlights subscriptions, recurring charges and bill spikes, with tailored spending insights to help you update your budget.

Visit

TL;DR

  • Reforecasting is a regular update of your budget using real income, bills and spending, not a new budget from scratch.
  • Do a 5-minute weekly check, a 30-minute monthly review and a longer quarterly reset.
  • Change the numbers that keep missing for two months in a row. A repeated miss usually means the target was sized wrong.
  • Track bills, subscriptions and price increases first, because they quietly move your fixed costs.
  • With friends, count what you owe and are owed as part of your forecast, so a group trip never surprises your balance.

Table of Contents

What budget reforecasting means

A budget is a plan: how much you expect to earn and where each dollar should go. A forecast is a prediction of what will actually happen in the weeks and months ahead. Reforecasting is the step in between. You take the plan, see how far real life has moved from it, and rebuild the forecast for what is left.

Top search results for this phrase mostly come from the business world, where finance teams reforecast quarterly. The idea is the same for a household, only simpler. Your “finance team” is you, and your reports are your bank and card statements.

Budgeting, forecasting and reforecasting side by side

Budgeting Forecasting Reforecasting
Question it answers Where should my money go? What will probably happen? Given what already happened, what should change?
Based on Goals and past habits Known income, bills and patterns Actual results versus plan
Looks at A month or a year Weeks to months ahead The rest of the period
When you do it Once, then on big changes Whenever you plan ahead Weekly, monthly and quarterly

You need all three. The budget sets direction, the forecast shows what is coming, and the reforecast keeps both honest.

Why a static budget fails

Most budgets fail for a boring reason: they were built from guesses. You assume $300 for groceries, then your real number is $380. You assume your phone bill stays the same, then a promotional rate ends. You assume a slow month socially, then three birthdays land in the same week.

A budget that never changes turns every miss into a feeling of failure. A reforecast turns the same miss into information. One personal finance planner puts it this way: a target missed by the same amount two months in a row is a mis-sized number, not a behavior problem. That is the mindset of this whole guide. You are not grading yourself. You are fixing the numbers.

How often to reforecast

Three rhythms cover most people. They add up to under an hour a month.

  1. Weekly, 5 minutes. Look at the two or three categories that usually run over, often dining out, groceries and shopping. You are checking for drift while it is still small.
  2. Monthly, about 30 minutes. The full review described below. One budgeting blogger recommends this kind of 30-minute monthly appointment in place of switching tools when a budget fails.
  3. Quarterly, about 45 minutes. Step back and re-check your income, your savings goals and your fixed costs such as rent, insurance and subscriptions.

Also reforecast immediately after a big change: a new job, a raise, fewer hours, a new roommate, a move, or a trip you just booked. Waiting for month end only means a longer stretch of working from a plan that no longer fits.

The monthly reforecast, step by step

Here is a routine you can repeat every month. It is built around how a cash flow plan works: instead of an abstract monthly total, you follow money as it arrives and leaves.

Step 1: Gather your actual numbers

Pull your bank and card activity for the month, your pay stubs and last month’s budget. Use real net pay (what landed in your account), not your salary on paper. If you have side income, tips or freelance work, record what you actually received.

Where it goes wrong: using projected numbers because they are easier to find. A forecast built on guessed income inherits the guess.

Step 2: Check balances against your records

Confirm that the balance in your tracker matches your real account balances. A mismatch usually means a missed transaction, a pending charge or a subscription you forgot. Fix it now, because every later step depends on a correct starting point.

Step 3: Compare planned and actual by category

List each category with the planned amount, the actual amount and the difference. Then label each difference:

  • One-time: a flight, a repair, a gift. It will not repeat.
  • Recurring overspend: it happened last month too.
  • Underspend: you spent less than planned. Decide whether to move the extra to savings.
  • Expected: it was seasonal or planned, such as a holiday month.

This labeling is what separates reforecasting from simply looking at your statement. The label tells you whether to change the plan or leave it alone.

Step 4: Diagnose the two or three categories that broke

Do not try to fix everything. Pick the few categories with the largest recurring gaps. Ask what changed: price, frequency, or a plan that was unrealistic from the start. Prices and frequencies are fixable. An unrealistic number should simply be resized.

A worked example. Say you planned $200 a month for dining out and spent $265 and $262 in the last two months. That is a recurring overspend of about $63. You have two honest options: raise the dining target to $260 and take the $60 from somewhere else, or cut back to a real $200 by changing your habits. What you should not do is leave $200 on the page and feel guilty. One planner suggests that a target missed by $60 two months in a row should rise by $60 rather than be punished with tighter limits, and then be balanced elsewhere.
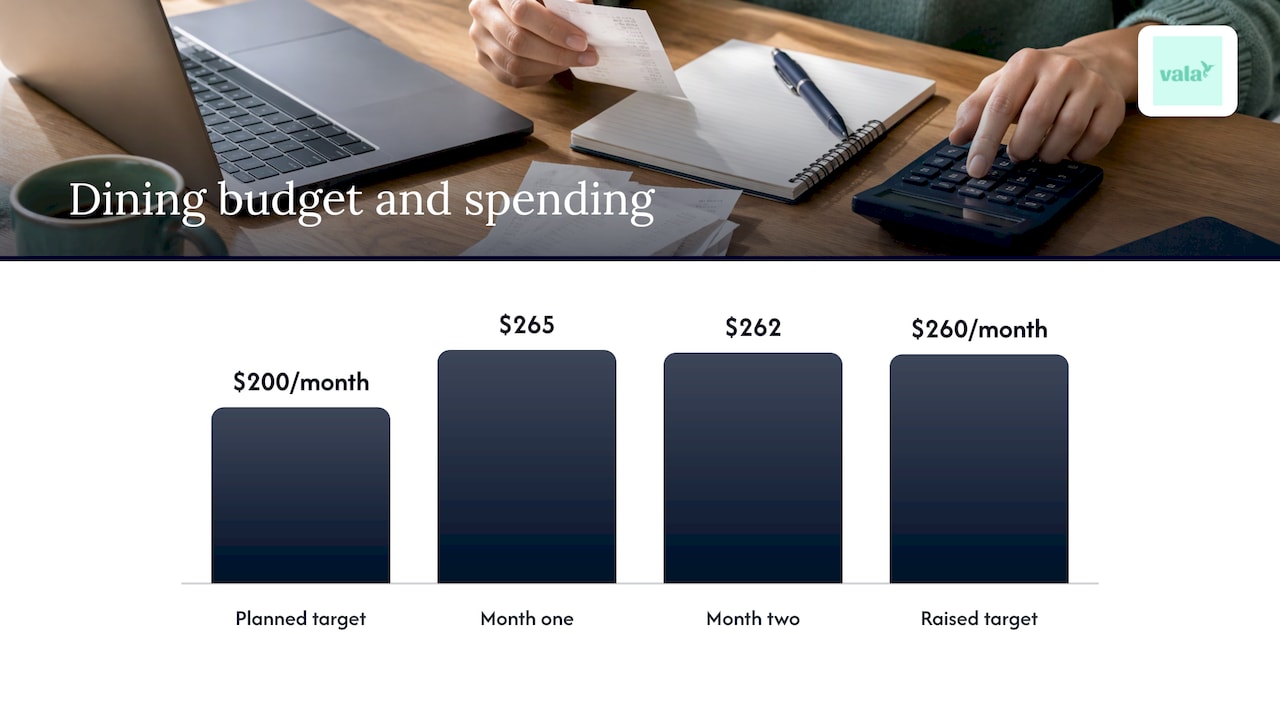
Step 4: Diagnose the two or three categories that broke

Step 5: Rebuild the next month week by week

This is the forecast part. The Consumer Financial Protection Bureau’s cash flow budget tool shows the method. After tracking at least one month, for each week you enter your beginning balance, add the income you receive that week, subtract all expenses including everyday spending, bills and savings, and carry the ending balance into next week. A positive result means you have enough to get through the week. A negative one means you will fall short, and you can fix it before it happens.
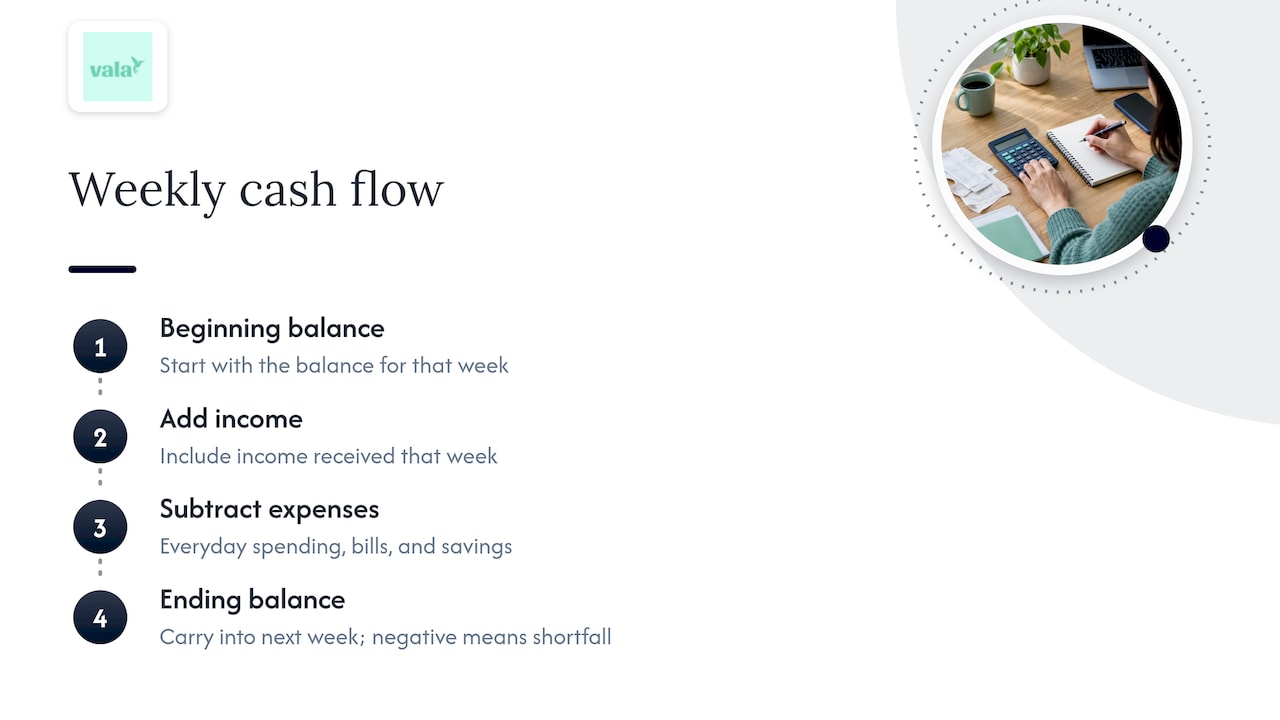
Weekly cash flow balance sequence

A university extension guide makes the same point: a cash flow plan shows the timing of income and expenses, not only the totals, and you balance each period so the ending balance is zero or above. Timing matters a lot if you are paid biweekly or your rent lands before your next paycheck.

Step 6: Write down the adjustments

Change the numbers, not your intentions. A good monthly reforecast ends with a short list: three numbers changed and one behavior to try. Keep the list short enough that you will actually follow it.

Adjusting for income changes and bill increases

Two things move a budget more than anything else: your income and your fixed costs.

When income changes. If you start a side hustle, lose hours or get a raise, rebuild the budget from the new take-home figure instead of patching the old one. If your pay is irregular, base the plan on a low-but-realistic month and treat anything above it as a bonus to assign: first to bills and savings, then to wants.

When a recurring charge goes up. Streaming plans, phone plans, insurance and gym memberships all raise prices. Since these are fixed costs, a $6 increase is $72 over a year, and you will not notice it in the day-to-day. Check your recurring charges at least once a quarter. Look for price changes, free trials that turned into paid plans and services you no longer use.

When a bill spikes. Utility bills move with the seasons. Look at the same month last year, or the last three months, and forecast the season instead of the average. Then set aside the difference in the cheaper months.

When irregular expenses hit. Car registration, annual subscriptions, holiday gifts and travel are predictable if you list them. Divide each by the months before it is due and put that amount into a sinking fund, which is just a savings pot for a known future cost.

Using the 50/30/20 rule as a sanity check

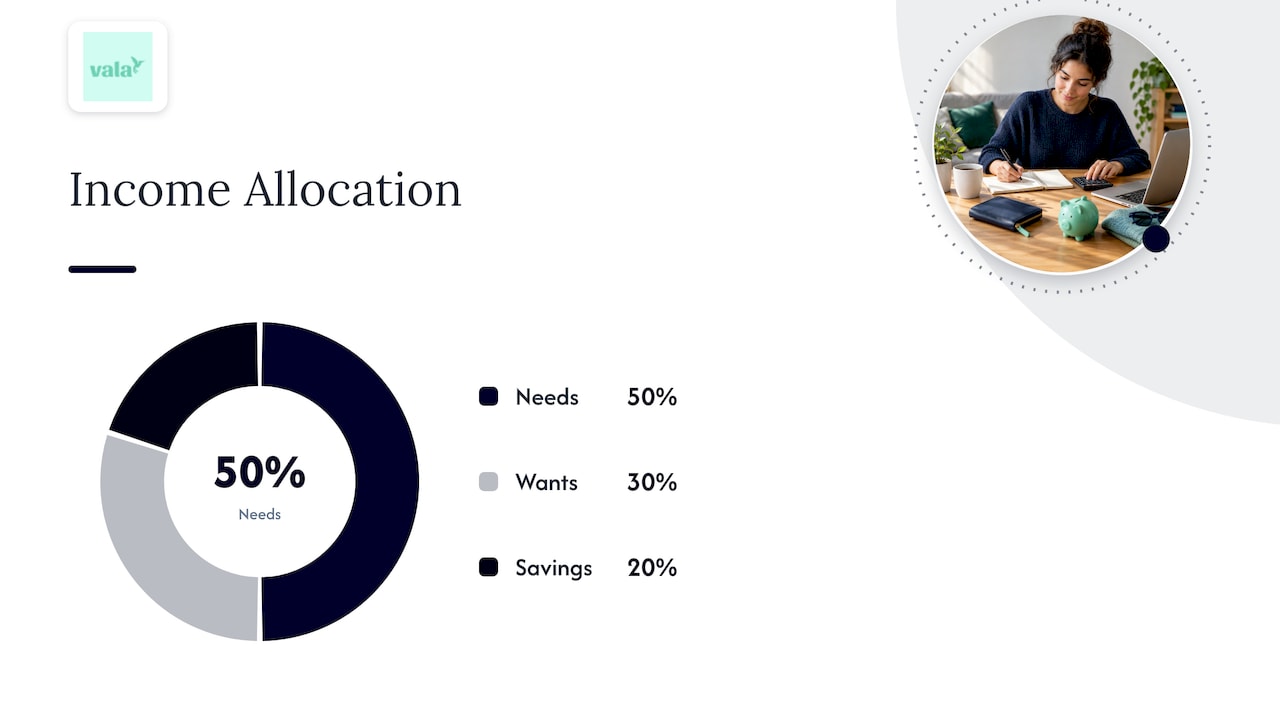
The 50/30/20 rule puts about 50% of after-tax income toward needs, 30% toward wants and 20% toward savings and debt payments. It is a rough guide, not a law, but it works well as a quick reforecast check. One budgeting blogger gives the example of needs creeping up to 58%, a drift you would spot by comparing your categories against the rule. If your rent is high, your needs share will naturally sit above 50%. The point is the trend, not the exact percentage: when one group grows, something else has to shrink or your income has to rise.

Reforecasting with friends: shared dining, trips and events

Shared costs are where a personal forecast most often breaks. You pay for the group dinner on your card, your balance drops by $240 and your dining category looks wrecked, even though your own share is $60. Or you owe a friend for your part of a rental and forget it until it lands.

A few habits fix this:

  • Separate what you paid from what you owe. Record the full amount you paid, then mark the part others owe you as money coming back. Your real spending is your share only.
  • Put expected reimbursements in the forecast by week. If a friend will pay you back on Friday, count it on Friday, not before. If you owe someone, count it in the week you plan to pay.
  • Settle often. Small balances settled right away are easier to forecast than a pile that builds across a whole trip.
  • Budget your share before the event. For a weekend trip, estimate transport, lodging, food and activities, divide by the number of people and add your share as a one-time line in the month it is paid.
  • Agree on the split rule up front. Equal split works for most dinners. For trips where people share unequally, such as one person driving or a bigger room, agree on the rule before spending starts.

If you are a couple sharing finances, the same logic applies at a bigger scale. Our guide to a budget tracking app for couples and shared expenses explains how to keep shared and personal money in one view.

Tools that make reforecasting easier

A spreadsheet works for a reforecast, and many people start there. The friction comes from entering data by hand, which is the first thing to slip when life gets busy. An app that connects to your accounts removes that step, so your monthly review starts with the actual numbers already in place.

If you want to see how the pieces fit, our guide to 13-week personal cash flow forecasting walks through the weekly view, and the monthly budget planner post gives you a layout to start from.

Make reforecasting automatic with Vala

Vala is built around the exact things a reforecast has to catch: subscriptions, recurring charges and bill spikes. It connects to your bank through Plaid, so your numbers come from your real accounts. It flags money leaks in your spending, sends reminders for upcoming bills and runs future cash flow simulations, so you can see next month before it arrives. It also handles shared and group expense splitting, so your forecast reflects your share, not the whole dinner check.

SaverLite is $2.99 per month. Start with the Money Leak Check to see which recurring charges and bill increases are costing you the most right now.
Valapoint

If you want to try bills first, the bill reminder app page shows how reminders keep due dates inside your forecast.

Our perspective

Most people think a budget fails because they lack discipline. We see it differently: it fails because it was never updated. A plan built on guesses will be wrong, and one that nobody revisits stays wrong.

That is why we built Vala around the leaks that change a budget behind your back: subscriptions that creep up, recurring charges you forgot and bills that jump without warning. These are not failures of willpower. They are changes in your numbers, and they should show up in your forecast as soon as they happen.

We also think budgeting should not feel like a monthly punishment. Tracking, bill reminders, future cash flow simulations and shared expense splitting all exist so the review is short, clear and calm. When your real numbers are already in front of you, reforecasting becomes a quick adjustment instead of a chore, and you can spend your energy on your goals.

SaverStride

FAQ

What is the difference between budgeting and reforecasting?

Budgeting sets your plan for how to use your income. Reforecasting updates that plan using real results, so the months ahead reflect what actually happened. You budget at the start and reforecast regularly after that.

How often should I reforecast my personal budget?

A good rhythm is a 5-minute weekly check on your riskiest categories, a 30-minute monthly review and a longer quarterly reset. Also update right away after a job change, a move or a major new bill.

What if I keep going over budget in the same category?

Treat it as a sizing problem first. If you have missed the target for two months in a row, raise it to a realistic number and take that money from another category. Then try one specific habit change, such as setting a weekly cap, instead of tightening everything at once.

How do I include shared expenses with friends in my forecast?

Record only your share as spending. Treat what friends owe you as incoming money in the week you expect it, and count what you owe as an outgoing payment. Settling up soon after each dinner or trip keeps your forecast clean.

Sources

Savings Buckets: How to Set Them Up and Make Them Work

Savings buckets are named pots of money, each with one job: an emergency fund, a trip, a laptop, a car repair. You can build them inside one savings account, across several accounts, or in a tracking app that labels your balance. The method works when every bucket has a target amount, a monthly contribution and an automatic transfer. At Vala, we built our savings goal tools around exactly that routine, and this guide walks you through it.

Valapoint
valapoint.com
Find More Room for Savings
Vala helps identify subscriptions, recurring charges, and bill spikes, so you can see where more of your money could go.

Visit

TL;DR

  • A savings bucket is a goal with a name, a target and a deadline. The bucket can be an account feature or just a label in your budget.
  • Start with 3 to 6 buckets, ordered from needs (emergency fund) to wants (vacation).
  • Contribution = (target minus what you have) divided by the months you have. Then automate it.
  • Buckets are labels, not extra insurance: FDIC coverage is still counted per bank and ownership category.
  • For group trips, each person funds a share of the same bucket on the same schedule.

Table of Contents

What savings buckets are (and what they are not)

The idea is simple. Instead of one savings balance that you mentally divide, you split it into goals you can see. If your balance is $4,000, a bucket view shows it as $1,500 for emergencies, $1,200 for a trip, $800 for car repairs and $500 for a new phone.

Three related terms get mixed up. A guide from Phroogal separates them this way:

  • Sinking fund: money you set aside gradually for a specific future expense, such as a trip or annual insurance premium.
  • Savings bucket: a separate space for a goal, often a feature inside a savings account.
  • Budget category: a purpose you assign money to inside your budget. You can track “Travel: $300, Holidays: $200, Car: $150” in a notes app without opening any account.

So a travel sinking fund is simply a savings bucket with a trip on the label and a date on the calendar. The terms overlap, and the habit behind all of them is the same: give each dollar a purpose before you are tempted to spend it.

Where your buckets can live

You have three practical options:

  1. Bucket or vault features inside a savings account. One account, several named goals, usually one shared interest rate.
  2. Separate savings accounts. Each goal gets its own account, which makes it harder to dip into by accident.
  3. A tracking layer on top of your accounts. An app or spreadsheet allocates your balance to goals without moving money.

Whichever you choose, remember what a label does not change. According to the FDIC, deposit insurance covers $250,000 per depositor, per insured bank, for each ownership category, and all your deposits in the same category at the same bank are added together. Ten buckets in one account are still one account for that limit. For most savers building a few thousand dollars of goals, this never matters. If your savings grow large, spread them across banks or ownership categories.

One more check before you commit to an account feature: ask whether a bucket can have its own transfers out and its own interest posting. If it cannot, as MyBankAnswers points out, it works as a planning label rather than a legally separate pot. That is fine for goals like a vacation. It simply tells you what the bucket is for.

Which goals deserve a bucket

Not every wish needs its own pot. WorkMoney suggests starting with 3 to 6 buckets, listed from needs to wants, each with an exact target. Too many buckets turns into bookkeeping, and bookkeeping is where good intentions stop.

A starter set for a salaried person or student in their 20s or 30s:

Bucket What it covers Priority
Emergency fund A job gap, a medical bill, a surprise repair 1
Irregular bills Annual fees, insurance premiums, car registration 2
Big purchase Laptop, phone, moving costs, furniture 3
Travel Flights, lodging, spending money 4
Fun and small projects Gifts, hobbies, concert tickets 5

The last row comes from FinHelp’s framework, which advises grouping small, similar goals into one bucket so you do not end up with a dozen tiny accounts. The same source ranks buckets in tiers for when you cannot fund everything at once: first an emergency cushion (it starts with one month of expenses) and any high-interest debt, then short-term buckets that prevent future emergencies, then the aspirational goals, funded a little at a time.

In plain terms: if money is tight, the trip waits until the emergency bucket has something in it. That is not a punishment. It is what keeps a flat tire from landing on a credit card.

Flat tire on a suburban roadside

How to size a bucket: the formula

A target without a deadline is a wish. Use this:

(Target − current balance) ÷ months to goal = monthly contribution

That is the required-savings-rate formula FinHelp describes. The CFPB’s savings booklet shows the same math at a smaller scale: $400 over 20 weeks is $20 a week, and you pick the frequency (weekly, monthly or per paycheck) that matches how you get paid.

Worked examples:

  • Laptop: $1,200 target, $200 already saved, 10 months. ($1,200 − $200) ÷ 10 = $100 a month.
  • Annual insurance premium: $780 due in 12 months, starting from zero. $780 ÷ 12 = $65 a month.
  • Emergency starter: $1,500 target, $300 saved, 9 months. $1,200 ÷ 9 is about $133 a month.

Add the monthly amounts. If the total is more than you can spare, do not shrink every bucket evenly. Stretch the deadline on the lowest-priority one first. If you want to test different timelines, our savings calculator shows how a monthly amount grows over time, and our guide to setting realistic savings targets helps you choose numbers you can keep up.

Automate it, then leave it alone

The formula only works if the money moves. WorkMoney’s guide offers a blunt reason: people tend to spend whatever they can see in their possession, so taking the money out of reach makes saving easier. In practice you have two routes:

  • Split your paycheck. If your employer allows direct deposit into more than one account, send a fixed amount straight to savings.
  • Schedule a transfer from checking to savings for the day after payday.

Set the transfer for the day after your money arrives, not the day before rent is due. Then handle changes on a schedule rather than in a panic. Review your buckets once a month for the first three months, then quarterly. When a raise comes, increase the top-priority bucket first. When a bill jumps, shift a small amount from the lowest-priority bucket and note the date you will restore it. Our walkthrough on automating personal savings goals covers the setup in more detail.

Reviewing progress and re-ranking goals as life changes is the part people skip. The same habit shows up in other planning areas too, such as the way baby milestone tracker benefits come from checking progress at regular points and adjusting the plan.

How to build a travel sinking fund

A travel sinking fund is the bucket most readers search for, and it is the easiest to start. The approach is to save for travel year-round, even when no trip is planned, then break the total into monthly goals. A $2,800 vacation eight months away is about $350 a month, so you can book without reaching for a card.

The cost of skipping this is real. One travel-planning guide from DollarFlourish illustrates a $3,000 trip eleven months out as a $250 monthly automated transfer, and notes that a vacation carried on a card at 24% APR can cost roughly a third more than its sticker price by the time you pay it off.

Steps:

  1. Pick a realistic total. Flights, lodging, food, local transport, a cushion of 10% for surprises.
  2. Pick a date. Even a rough season works. “Next summer” gives you a month count.
  3. Divide. Use the formula above.
  4. Name the bucket after the trip. Seeing “Lisbon 2027” next to the balance makes it harder to raid.
  5. Automate and check monthly. If prices rise, adjust the contribution rather than the destination at the last minute.

Saving with friends for a shared trip or event

Group trips go wrong in a predictable way: one person books everything on a card and spends months chasing payments. A shared bucket plan avoids that.

Say four friends plan a cabin weekend that costs $2,400 in total, six months out. That is $600 each, or $100 a month per person. Each friend moves $100 into their own travel bucket on payday. When it is time to book, everyone has their share ready and nobody fronts the whole bill.

A few rules keep it smooth:

  • Agree on the total and the split before anyone saves. Equal shares are easiest. If rooms differ in price, split by room.
  • Decide what counts as shared. Lodging and the rental car, yes. Individual meals, maybe not.
  • Keep a single running record of who has paid what, including on-the-trip costs like dinners and gas.
  • Settle quickly. The longer a small debt sits, the more awkward it gets.

This is where our app helps. Vala includes automated group and shared expense splitting that connects to your overall budget view, so a friend’s dinner share and your own savings contribution sit in the same picture instead of in separate notes and chats.

Common mistakes

  • Too many buckets. Six well-funded buckets beat fifteen empty ones.
  • No deadline. Without a date you cannot calculate the monthly amount.
  • Treating buckets as a spending permission slip. Moving money between buckets is easy, which is the feature and the risk. If you often reassign money, put a rule in writing: any move from the emergency bucket needs a real emergency.
  • Funding the fun bucket first. Needs go first, as above.
  • Ignoring recurring charges. Subscriptions you forgot about quietly shrink the amount you can send to buckets each month. Finding them is often the quickest way to free up bucket money.

Perspective

We see savings buckets as a clarity tool, not a willpower test. The hard part is rarely the idea. It is knowing how much you can really send to each goal after rent, bills and the charges you stopped noticing.

That is why we start with a money leak check before any bucket plan. When you know which subscriptions and recurring charges are draining your account, the number you can put toward a trip or an emergency fund becomes honest, and the plan holds up.

Our approach connects the pieces: savings goals, bill reminders, future cash flow simulations and shared expenses in one view, rather than a separate spreadsheet for each. We want you to feel confident that each bucket is funded on time and that nothing surprising is coming next month.

SaverStride

Put your buckets on autopilot with Vala

Vala’s Money Leak Check looks for the subscriptions, recurring charges and bill spikes that eat into your savings room, using secure bank integration through Plaid. Our plans include SaverLite at $2.99 per month and SaverPro at $5.99 per month, with savings goal management, bill reminders and shared expense splitting in the paid tiers.

Valapoint

Start with the Money Leak Check to see how much you can free up, then give each dollar a bucket. You can also look at our automatic savings app page for how goals and transfers work together, or use the goal tracker for savings milestones to follow your progress.

FAQ

Are savings buckets the same as sinking funds?

They overlap. A sinking fund is the habit of saving gradually for a known future expense. A bucket is the container, whether an account feature, a separate account or a label in your budget. A travel sinking fund is a bucket with a trip name and a date.

How many savings buckets should I have?

Start with 3 to 6. Put needs like an emergency fund and irregular bills first, then wants like travel. Group small goals such as gifts and hobbies into one bucket so you can keep track of them without extra effort.

Does using buckets raise my FDIC insurance?

No. FDIC coverage is $250,000 per depositor, per insured bank, per ownership category, and your deposits in the same category at one bank are added together. Buckets inside one account do not change that total.

How much should I put in a bucket each month?

Subtract what you already have from the target, then divide by the months you have. A $2,800 trip eight months away comes to about $350 a month. Choose weekly, monthly or per-paycheck transfers to match your income schedule.

Can I use buckets without opening new accounts?

Yes. A budget category or an app label lets you assign your balance to goals without moving money. Moving money into a separate account adds a bit more friction, which some people like for goals they do not want to touch.

Sources

Streaming Subscription Management: Track, Rotate, Cancel

The simplest way to manage streaming subscriptions is to keep one list of every service, with its price and renewal date. Then keep only the services you are watching this month. Everything else gets paused or canceled, and a reminder brings it back when a show you want arrives. You can do this with a spreadsheet and a calendar. If you want the list built from your real charges, Vala’s Money Leak Check reviews your recurring charges, and our bill reminders warn you before each renewal.

Valapoint
See recurring charges more clearly
Valapoint identifies subscriptions and other recurring charges, helping you spot spending patterns and potential savings opportunities.

TL;DR

  • List every streaming service by checking your TV apps, app store subscriptions and card statements, then note the price and renewal date of each.
  • Cancel where you signed up. Deleting the app does not stop billing.
  • Rotate: keep one or two services at a time and bring the others back only when a show you want arrives.
  • Set a reminder 3 to 7 days before each renewal, and check your next statement to confirm a canceled charge stopped.
  • If you share a plan, write down who pays what and settle up every month.

Table of Contents

Why streaming costs creep up

Most people do not choose to pay for six services. They sign up for one series, finish it, and never cancel. Consumer Reports describes this pattern: the service becomes part of the monthly bills like a utility, even though streaming services do not require contracts.

The habit is common. According to Antenna, as cited by Consumer Reports, more than 29 million Americans, about one-quarter of paying streaming subscribers, canceled three or more services over the past two years. Canceling and returning is normal behavior, and the services expect it.

The cost is easy to miss because each charge is small. A $9 charge here and a $16 charge there do not stand out on a statement. Added up across a year, they do. Our guide to subscription creep shows how to spot this on three statements.

Step 1: Build one list of every streaming service

You cannot manage what you cannot see. Consumer Reports advises listing every streaming service by checking your TV apps and your credit card bills. Start there, then widen the search, because streaming charges show up in more than one place.

Check these four places:

  1. Your TV and streaming device. Open the app row on your smart TV, streaming stick or game console. Every app you have signed into is a candidate.
  2. App store subscriptions. On an iPhone, go to Settings, tap your name, then Subscriptions. On Android, open the Play Store, tap your picture, then Payments & subscriptions. Steady Tap’s guide walks through these paths, along with the ones for Roku and Amazon.
  3. Amazon, Roku and other billing hubs. Channels added through Amazon or Roku bill through those accounts, not the streaming service itself.
  4. Card and bank statements. Look back at least 90 days. Search for the service names, and also for odd merchant descriptors you do not recognize.

Then put the results in a table with four columns:

Service Monthly price Billed through Renewal date
Example streaming service A $ Direct on its website Day of the month
Example streaming service B $ Apple Day of the month
Example streaming service C $ Amazon Day of the month

The “billed through” column matters most. It tells you where you will have to go to cancel. It also catches duplicates, such as the same service paid for once directly and once through an app store.

Building this by hand takes an hour or two the first time. Vala connects to your bank through Plaid, so the recurring charges appear in one place, and our recurring subscription review flags the ones worth a second look. Our quick audit guide and the subscription audit checklist give you the manual version of the same routine.

Add up the real total

Once the list exists, add the monthly column and multiply by 12. That annual number is the one that changes behavior. Our free subscription cost calculator does the math for you.

Step 2: Decide what each service earns

Go down the list and put one word next to each service: keep, pause or cancel. Ask three questions:

  • Did you open it in the last 30 days?
  • Is there a show or sport on it you plan to watch in the next month?
  • Does something you already pay for include it? Steady Tap points out that some phone, internet or store memberships include a streaming app, so you may be paying twice.

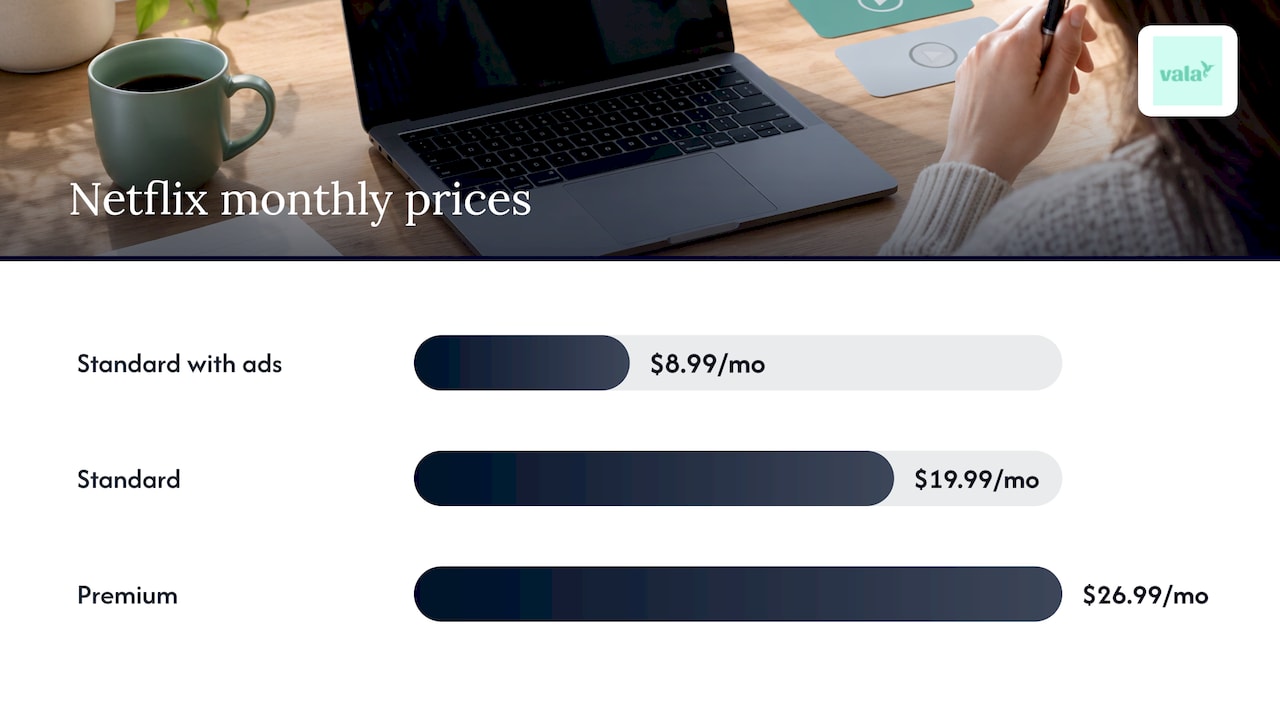
Also check the plan tier. Steady Tap suggests choosing a plan with ads where you can, and treating bundles carefully, since a bundle only saves money if you watch everything in it. For a sense of the spread, Netflix lists its US plans and pricing as $8.99 a month for Standard with ads, $19.99 for Standard and $26.99 for Premium. Prices change, so confirm on the service’s own page before you decide.

If a price just went up, run our 15 minute price hike test. It helps you decide whether the service still earns its place at the new price.

Step 2: Decide what each service earns

Step 3: Cancel the right way

The most common cancellation mistake is canceling in the wrong place. The rule is simple: cancel with whoever bills you.

  • Billed directly. Sign in on the service’s website, open Account, and look for Cancel or Manage plan.
  • Billed by Apple or Google. Cancel in your Subscriptions settings, using the paths in step 1.
  • Billed by Amazon or Roku. Cancel in that account’s subscriptions or channels page.
  • Billed by a partner, such as a phone carrier or internet provider. Cancel with that company.

Deleting the app does nothing. Crunchyroll’s help center says deleting the app, logging out or removing a payment method does not cancel a subscription. You keep being charged until you cancel.

What the law says about canceling

Canceling should not be a maze. The FTC’s stipulated order in an enforcement case describes the standard for a negative option, which is a charge that continues unless you act: the way to cancel must be easy to find, easy to use, and must not require unnecessary steps. It also says that if you signed up online or in an app, cancellation must be offered through the same website or app. That order applies to the company in that case, but it shows the standard regulators apply.

The New York Attorney General’s consumer alert makes the same point: canceling should be as easy as signing up, and you should not face delays from repeated attempts to “save the sale.” If a service makes you jump through hoops, take screenshots as you go. They help if you later dispute a charge with your card issuer.

If you cannot cancel online and the charge continues, contact your card issuer or your state attorney general’s consumer protection office.

For a longer walkthrough, see our step-by-step cancellation plan.

Confirm the charge stopped

Canceling is not finished until you check:

  1. Look for a confirmation email the same day.
  2. Check that the account shows an end date. Crunchyroll explains that a future end date means the membership is canceled but still active, and the next charge, if any, covers your final billing cycle.
  3. Look at your next card statement. A final charge is normal if you canceled on or after the renewal date.
  4. If a charge still appears with no active membership, it may come from another email address or a third-party billing account, such as Apple or Google. Search your email for that service under each address you use.

This last check is where a connected tool earns its keep. Vala watches your recurring charges, so a charge that should have ended and did not shows up in your review instead of three months later.

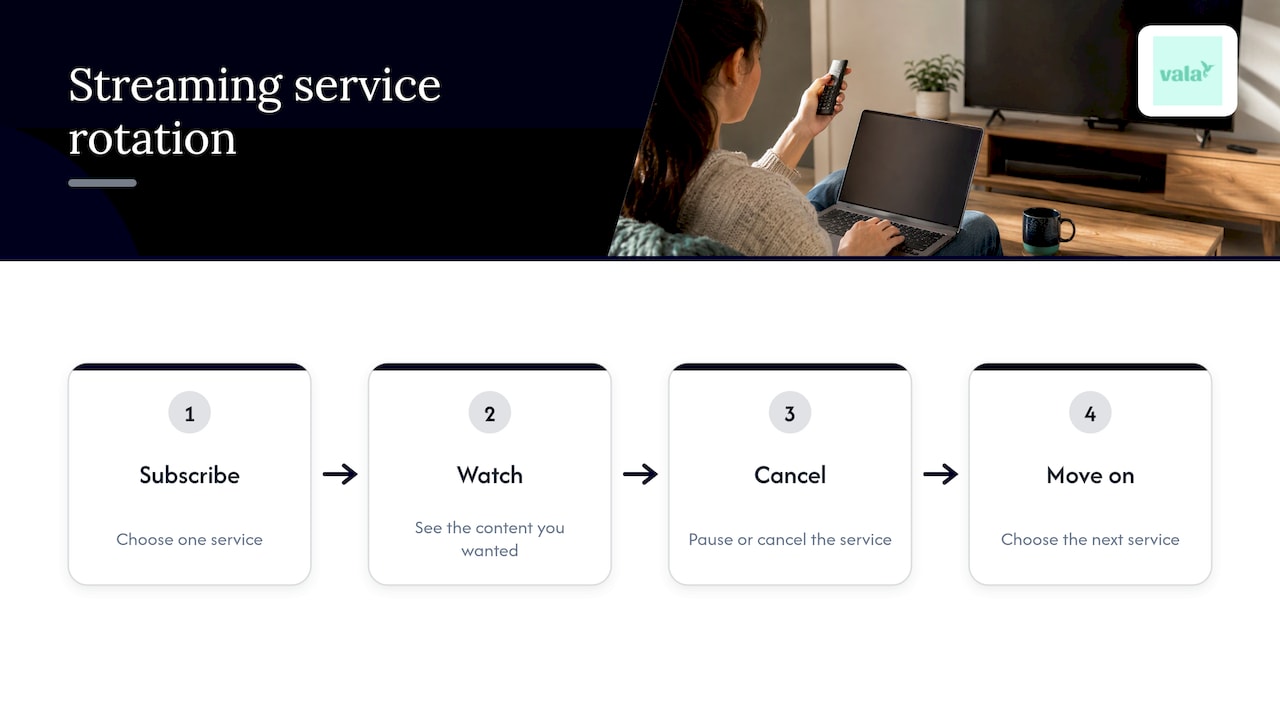
Step 4: Rotate services instead of keeping all of them

Rotation is the biggest saver. The idea is to subscribe to a service, watch what you wanted, cancel, then move to the next one.

Four steps for rotating streaming services

NerdWallet’s writer calls this round-robin streaming. You pause or cancel every app except one, watch it until you run out of things you want to see, then move on. After a year, the author reported cutting average streaming spending from $89 a month to $20, about $833 a year. That is one person’s result in Canadian dollars, not a promise, but the method works the same way in the US. Cheapism makes a similar point, saying rotation can bring a $60 monthly bill down to about $20.

A simple rotation routine

  1. Make a watchlist. Write down the shows, movies and sports you actually want, and which service carries each one.
  2. Group by service. If three things you want sit on one service, that is the one to subscribe to next.
  3. Choose monthly billing. Cheapism recommends monthly plans so you can cancel at any time.
  4. Pause when possible. NerdWallet notes that most services let you cancel and come back with no penalty. Some allow pausing: Curiosity Stream and Highball.tv for up to 12 weeks, and Netflix for up to 30 days, though not on every plan or payment method. Prime Video must be canceled and restarted as a standalone service, although you can pause your whole Prime membership.
  5. Set the cancel reminder at sign-up. The moment you subscribe, schedule a reminder for 3 to 7 days before the next billing date. NerdWallet’s author uses a reminder a week before and another the day before.
  6. Cancel as soon as you finish. You can usually keep watching until the paid period ends, so there is no reason to wait.

The same keep-or-skip thinking works for any large planned purchase. For example, a guide to building a baby registry on a budget applies the same idea of choosing only what you will actually use.

Handy rules to keep rotation honest

  • One in, one out. Any new service has to replace an old one.
  • Quarterly check. Every three months, repeat the list from step 1. New charges sneak in, and trials turn into paid plans.
  • Free trial discipline. The Ohio Attorney General advises setting a calendar reminder immediately after signing up for a free trial, and not entering payment information unless you are sure you will cancel on time. It also suggests requiring a password for purchases in your app store settings.

Step 5: Share plans without the awkward math

Shared plans are where subscription management gets social. Friends split a plan, one person pays the bill, and nobody remembers who owes what.

Start with what the service allows. Netflix, for example, lets a Standard plan add one extra member who does not live with you, for $7.99 a month with ads or $9.99 without, while Premium allows up to two (Netflix pricing). Rules differ by service and change, so check the plan’s own page before you set up sharing.

Then keep it simple:

  1. Name one payer for each plan, and put that on your list.
  2. Write the split next to the service: each person’s share and the day it is due.
  3. Settle monthly, not whenever someone remembers.
  4. Agree on what happens when someone leaves. Do you cancel, or split among those left?
  5. Rotate the payer if the same person keeps fronting the cost.

Vala handles shared expenses with automated group and shared expense splitting, so the monthly cost of a shared plan stays attached to the people who use it, alongside your own budget. If you split dinners, trips and subscriptions with the same friends, it keeps all of that in one place.

Perspective

Streaming is rarely the real problem. The real problem is that recurring charges are built to be forgotten, and most budgeting tools only show you what already happened.

We built Vala around a different idea: find the leaks, then make a plan to recover the money. For streaming, that means seeing every recurring charge in one view, getting a reminder before a renewal, and checking your future cash flow before you add another service.

A list and a calendar will take you a long way, and you should start there today. When you want the list to stay current without a monthly chore, connecting your accounts securely through Plaid, reviewing recurring charges and getting bill reminders is what Vala is designed to do. Streaming, shared plans and the rest of your household budget end up in one clear picture.

SaverStride

Put the routine on autopilot

A manual routine works, but it depends on you remembering to do it. Vala’s Money Leak Check looks at your spending for hidden recurring charges, including streaming plans you forgot about. Vala’s SaverLite plan is $2.99 per month, and you can start with the Money Leak Check to see what turns up. To go deeper on the topic, our hidden recurring charges page shows what to look for.

Valapoint

Pair it with bill reminders so a renewal never arrives as a surprise.

A 30 minute starter plan

If you do only one thing this week, do this:

  • Minutes 1 to 10: Open your app store subscriptions, your TV apps and your last 90 days of statements. Write every streaming charge in the table.
  • Minutes 11 to 20: Mark each as keep, pause or cancel. Cancel what you have not opened in a month.
  • Minutes 21 to 25: Set a renewal reminder for everything you keep.
  • Minutes 26 to 30: Write your watchlist and decide which service comes next.

Then look at your next statement. It is the last check, and the one that shows whether your plan worked. For other places the same method pays off, see our guide to unnecessary recurring expenses.

FAQ

How do I manage all my subscriptions in one place?

Start with a single list that records each service, its price, who bills you and its renewal date. Pull the entries from your app store subscriptions, your card statements and your TV apps. To keep the list current, use an app that reads your recurring charges, or repeat the check every quarter.

What is the best way to cancel streaming services?

Cancel with whoever bills you: the service’s website, Apple, Google, Amazon, Roku or a partner company. Deleting the app does not cancel anything. Afterward, look for a confirmation email and an end date on the account, then check your next statement.

Is it worth rotating streaming services?

For most households, yes. Services do not require contracts, and most let you cancel and return without a penalty. Watching one or two services at a time instead of all of them can cut a bill sharply, as the Cheapism example of $60 down to about $20 shows. Set a reminder at sign-up so you cancel on time.

Why was I charged after I canceled?

The most common reason is timing: if you canceled on or after the renewal date, one final charge is normal. Other causes are a second account under another email address or a subscription billed through Apple or Google. If none of these explains it, contact the service, then your card issuer.

Sources

Student Loan Budgeting: How to Fit Repayment Into Your Month

Student loan budgeting comes down to three moves. List every loan and its due date. Put the required payment in your budget first, as a fixed cost. Then divide what’s left between everyday spending, savings and any extra payments. If the payment still doesn’t fit, you have federal options to lower it, and the sooner you ask, the more choices you have.

This guide walks through each move with real numbers. It covers budgeting while you’re still in school and after you graduate. It also covers how to decide which loan to pay first and what to do if you fall behind.

Valapoint
Find Room in Your Monthly Budget
Vala highlights subscriptions, recurring charges and bill spikes, helping you spot potential savings as you plan for student loan payments.

Explore Vala

TL;DR

  • Gather every loan’s balance, interest rate, minimum payment, loan type (federal or private) and servicer before you build anything.
  • Treat the minimum payment as a fixed cost. One common guide is the 50/30/20 rule, with loans split between needs and savings.
  • Turn lump sums like financial aid refunds into a monthly amount by dividing them by the months they must last.
  • Pay extra only after you have a starter emergency fund and any employer retirement match, then aim at the highest-interest loan.
  • If a payment doesn’t fit, call your servicer before you miss one. Federal borrowers can ask about an income-driven plan.

Table of Contents

Start with a full list of your loans

You can’t budget for a payment you haven’t pinned down. Sallie Mae says the first step is to figure out what loans you have, how much your payments will be and when they are due.

A simple list works. For each loan, write down:

  • The current balance
  • The interest rate
  • The monthly minimum payment
  • Whether it is federal or private
  • Your servicer’s name and contact details

Navy Federal Credit Union recommends keeping all of this in one place, and the list takes about twenty minutes to build. It also makes the later decisions easier: which loan to pay first, whether to ask for a different plan, and how much room you really have.

Know when payments start

For most federal loans, you have a six-month grace period after you graduate, leave school or drop below half-time enrollment. MOHELA explains that interest still accrues on most loans during that time and is added as unpaid interest to your balance, though it isn’t capitalized yet.

Use those six months as practice. Federal Student Aid notes that adding the payment to your expenses has a big impact on your budget, so update the budget to include loan payments, new income and new living costs. If you can live on your budget with a pretend loan payment moved into savings, the first real bill won’t be a shock.

Build the monthly budget

Federal Student Aid lays out the basic steps in its repayment checklist: set a timeframe and goals, pick a budgeting tool that works for you, list your income and expenses, subtract expenses from income, and adjust if you have a shortfall.

Step 1: Find your real monthly income

Use take-home pay, not salary. Navy Federal suggests counting income after taxes and deductions, including every source. If your income changes from month to month, use your lowest typical month as the baseline. Anything above that becomes a bonus you can assign to savings or extra payments.

Step 2: List fixed costs first

Chase classes student loan payments as a fixed expense, alongside rent, car payments, subscriptions and insurance, and suggests setting money aside for fixed costs before other line items. That order matters. The loan payment has a due date and a penalty for missing it, so it comes off the top.

Subscriptions are fixed costs too, and they are easy to forget. Streaming, apps, cloud storage and gym memberships can add up to real money, and you may not notice one you stopped using. A money leak check is a quick way to see recurring charges in one list so you can decide which ones stay.

Step 3: Set limits for everything else

Variable costs are groceries, gas, dining out, shopping and fun. Give each a monthly limit. Track your spending for a month or two, then adjust the limits based on what actually happened rather than what you hoped would happen.

If you want a ready-made template, our monthly budget planner guide walks through the layout.

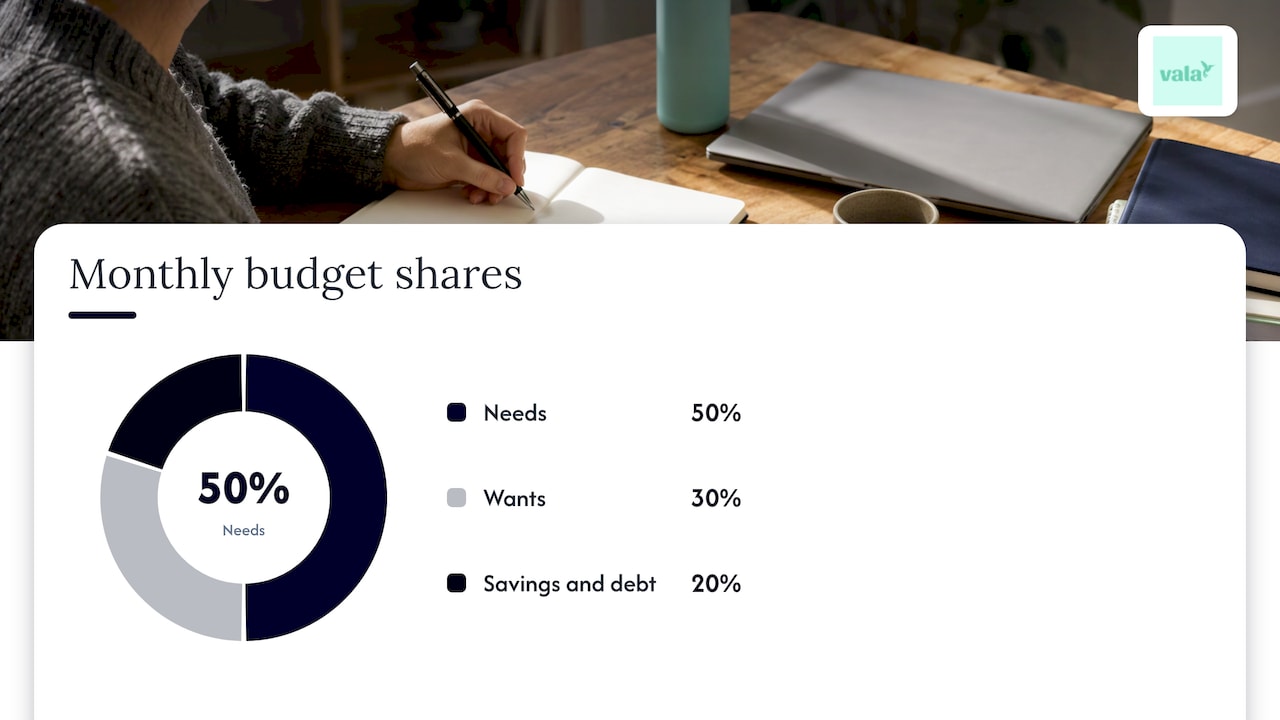
Using the 50/30/20 rule with student loans

The 50/30/20 rule is a starting point many lenders and publications use. Sallie Mae describes it this way: 50% of your budget for necessities such as rent, utilities, transportation, insurance and groceries, 30% for wants such as dining out and entertainment, and 20% for savings and debt repayment, including student loans.

Here is a made-up example. Say you take home $3,000 a month.

Category Share Amount What goes in it
Needs 50% $1,500 Rent, utilities, groceries, transportation, insurance, minimum loan payment
Wants 30% $900 Dining out, shopping, entertainment, subscriptions you chose
Savings and extra debt 20% $600 Emergency fund, retirement, extra loan payments

Where should the loan go? Admire.org places the minimum payment in the needs bucket and anything above the minimum in the savings bucket, since extra payments are a choice. That split is a practical way to see how much room you have for extra payments.

If the minimum payment pushes needs well above 50%, that’s common, especially in expensive cities. Don’t give up on the plan. Trim wants first, and see the section on adjusting expenses below.

Using the 50/30/20 rule with student loans

A sanity check on the size of the payment

As a rough guide, U.S. News reports that Department of Education guidelines suggest student debt payments stay around or below 20% of discretionary income, or 8% of total income. MOHELA advises that if your payment is more than 10 or 15 percent of your income, you should contact it to explore a different repayment option.

If your payment is above those marks, don’t just cut your food budget to the bone. Ask about other plans first (see below).

Budgeting while you’re still in school

If you’re a student, your income may be a lump sum: a financial aid refund, savings or a loan disbursement. Spread it out so it lasts.

The rule from Duke University’s Office of Student Loans & Personal Finance is to divide the money by the number of months it needs to cover. Their example: $5,000 in savings used over nine months, mid-August to mid-May, gives a monthly income of $555.55.

The same applies to borrowing. Say you borrow $6,000 to cover four months. That’s a monthly budget of $1,500 ($6,000 divided by 4), and you have to hold yourself to it each month, as one university budgeting guide from CCSF puts it, by knowing what is coming in and when each expense is due.

Two habits help:

  • Plan for a late refund. Duke advises assuming refunds won’t arrive until two to three weeks into the semester, so have another source ready for early expenses.
  • Borrow only what the budget needs. Every dollar you borrow has to be repaid with interest, so a monthly figure makes it easier to see when you’re taking more than you’ll use.

For more on student money, see our guides on how to manage finances as a student, a student budget checklist and why student budgeting is different.

Making room: where to adjust

If the payment takes a big share of each paycheck, Fidelity suggests looking at savings on groceries, rent, utilities, gas, commuting, dining out and health care. You don’t need to cut everything. Pick the one or two areas where a change is easy to keep.

A short order that works for many people:

  1. Recurring charges. Cancel or pause what you don’t use. This costs you nothing in daily life.
  2. Dining out and delivery. Cut back instead of cutting out, and set a weekly limit.
  3. Groceries and utilities. Small habits, like planning meals, add up over a year.
  4. Housing and transportation. The biggest levers, but they take longer. Roommates or a cheaper commute can change the whole picture.

Our penny saver habits guide has daily moves that make this easier to keep up.

Also build a little cushion. Navy Federal recommends starting an emergency fund with $500 to $1,000, working toward one month of expenses, and keeping it in a separate high-yield savings account. A cushion keeps a surprise car repair from becoming a missed loan payment.

Automate the payment

Autopay protects you from forgetting. Federal Student Aid says automatic debit takes payments from your bank account each month, and borrowers with Direct Loans may get a 0.25% interest rate reduction for enrolling.

Set the payment date for a day or two after payday. Then add a reminder for the bills that are not automatic. Bill reminders are one of the things Vala is built for, so you see upcoming charges before they land.

Paying extra: when it makes sense

The minimum keeps you in good standing. Paying more cuts interest. But the order of your priorities matters.

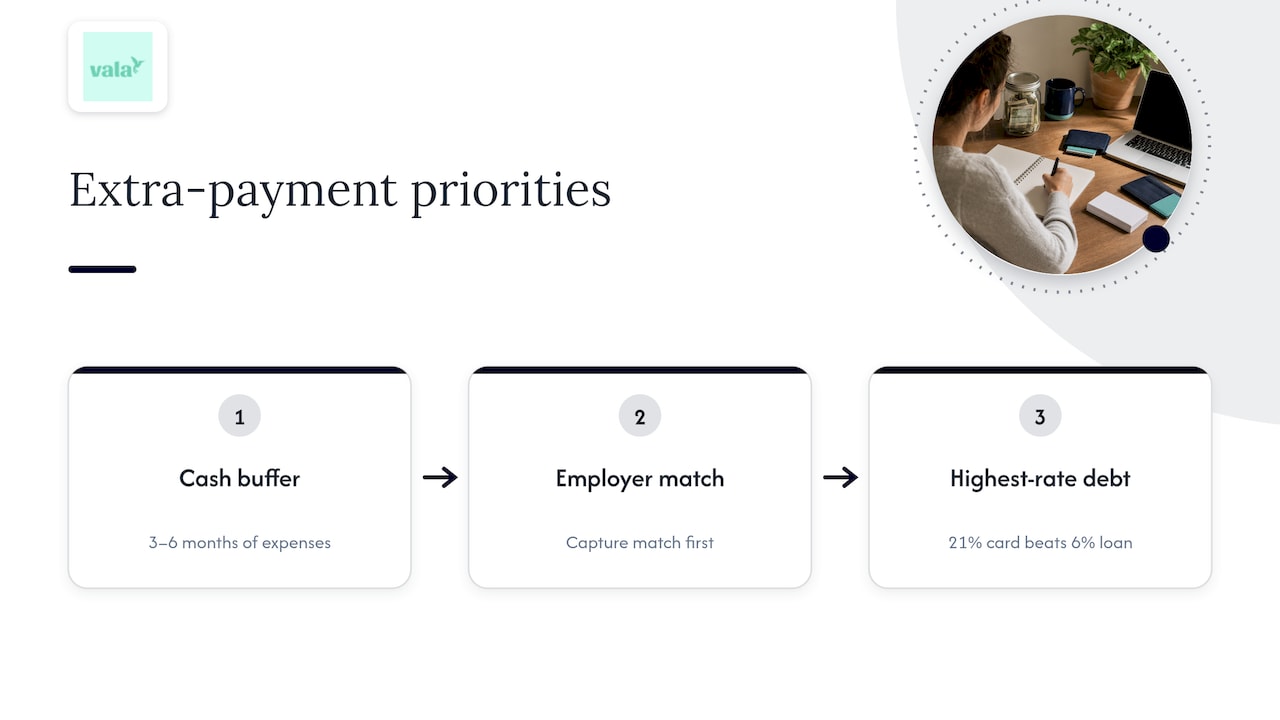
Before you pay extra

U.S. News advises building an emergency fund of three to six months of expenses and capturing any employer retirement match first. If you carry other debt, it says extra money should go to the one with the highest interest rate. A credit card at 21% beats a student loan at 6%.

Three priorities before paying extra on loans

Admire.org gives a gentler path: reach one month of expenses, then three, before you start extra loan payments. Either way, a cash buffer comes first.

Which loan to pay first

Two common methods, as ELFI describes them:

  • Debt avalanche: pay the highest interest rate first. This saves the most interest.
  • Debt snowball: pay the smallest balance first. This gives you quick wins that keep you motivated.

With similar rates, ELFI says unsubsidized loans make sense first, because they accrue interest from the day they are disbursed.

Private versus federal matters too. Investopedia says prioritizing private loans often makes sense, because federal loans offer more flexibility. Under some income-driven plans, federal payments can be as low as $0, and public service workers could be eligible for Public Service Loan Forgiveness after 120 monthly payments.

How federal servicers apply extra money

If you pay more than what’s due on federal loans, Edfinancial Services says the overpayment goes to the loan with the highest interest rate first. If rates match, it goes to unsubsidized loans, then subsidized. There’s no prepayment penalty. If you want the extra to hit a specific loan, contact your servicer and ask how to direct it.

If the payment doesn’t fit

This is the part many people avoid, and it’s the part where acting early helps most.

Call your servicer first. Federal Student Aid says a loan is delinquent if you miss even one payment, and late fees may apply. If you can’t pay, contact your servicer right away. It can talk through changing repayment plans, deferment, forbearance and consolidation.

Ask about an income-driven plan. The Consumer Financial Protection Bureau says an income-driven repayment plan can lower your monthly payment to as low as $0, and the Education Department’s Loan Simulator can help you choose. These plans require paperwork every year, so set a reminder a month early. The CFPB’s debt booklet adds that payments are based on family size and household income, you don’t need a job to qualify, and there is never a fee to change your plan.

Know the stakes of default. The CFPB warns that defaulting on a federal loan (missing nine or more payments) can lead to wage and tax refund garnishment and credit problems. That’s why a call now beats silence later.

Private loans are different. The CFPB notes that federal loans offer several repayment plans unlike most private student loans. If you have private loans, call the lender and ask what hardship options exist.

Use tools to stay on track

A budget only works if you look at it. Pick a tool you’ll actually open, whether that’s a spreadsheet or an app. The habit that matters most is a short weekly check: What came in? What went out? Is the loan payment covered?

This is where building financial literacy skills pays off over time. Budgeting technology can balance loan payments, everyday expenses and savings in one view, so you spend less time on the math and more time making decisions. If you’re comparing options, our guide to the best budget app for college students covers what to look for.

Perspective: why we start with leaks, not limits

Most advice about student loans starts with cutting back. We start by finding money you didn’t know you were losing.

Many budgets don’t fail because of a big purchase. They fail because small recurring charges, forgotten subscriptions and bill spikes quietly take a share of every month. When you recover that money first, the loan payment feels lighter without a single painful cut.

That’s why we built Vala around money leak detection, recurring charge review and a clear recovery plan, rather than a dashboard that only tracks what already happened. Connecting your bank through Plaid lets the app show where money goes. Future cash flow simulations let you see how a payment, or an extra one, will affect the weeks ahead.

For borrowers, we think this is the most practical way to budget: protect the loan payment, plug the leaks, then decide where the recovered money goes. Our customers report ongoing progress toward their savings goals this way.

SaverStride

See where your payment room is hiding

If you want to find extra room for your loan payment, start with a look at your recurring charges. Vala’s Money Leak Check scans your spending for subscriptions, repeat charges and bill spikes, and gives you a plan to recover the money. You can also share costs with friends or a partner, which helps if you split rent, trips or dinners.

Valapoint

SaverLite is $2.99 per month, and SaverPro is our fuller plan. Start your free money leak check and see what you could put toward your loans.

A simple monthly routine

Once the budget exists, keep it small and repeatable:

  1. Payday: Confirm the loan payment is covered and set aside savings first.
  2. Weekly, 10 minutes: Check spending against your limits and note any new recurring charges.
  3. Monthly: Compare planned and actual spending, then adjust limits. If you have a surplus, send it where your priorities say: emergency fund, match, then the highest-interest debt.
  4. Yearly: If you’re on an income-driven plan, renew your paperwork on time. Review your loans and rates, and redo the budget when your income changes.

If you’re budgeting as a young professional with a first salary, our financial planning for young professionals guide helps you plan for what comes next, and our family budget planner is a good fit if you’re budgeting for a household.

FAQ

How much of my income should go to student loans?

There’s no single number. U.S. News reports that Department of Education guidelines suggest keeping payments around or below 8% of total income. If you’re well above that, ask your servicer about other repayment options.

Is a student loan payment a need or a want?

The required minimum is a need. It has a due date and penalties, so it belongs with rent and groceries. Admire.org puts anything above the minimum in the savings category, since extra payments are your choice.

Should I pay off student loans or build an emergency fund first?

Build at least a starter emergency fund first. Navy Federal suggests starting with $500 to $1,000, then working toward one month of expenses. A cushion keeps a surprise bill from forcing you to miss a loan payment or use a credit card.

What if I can’t make my payment this month?

Contact your servicer before the due date. Federal Student Aid says even one missed payment makes a loan delinquent. Your servicer can discuss changing plans, deferment, forbearance or consolidation, and federal borrowers can apply for an income-driven plan.

Sources

How to Merge Finances After Marriage: A Practical Plan

The best way to merge finances after marriage is the one you both agree on, not one default setup. Most couples choose one of three models: everything together, everything separate, or a joint account for shared costs plus personal accounts. Start with an honest look at income, debt and spending, then pick the structure that fits. Then automate it so it runs without constant negotiation.

This guide walks you through each model, how to split bills when you earn different amounts, a step-by-step plan, and the safeguards that keep both of you secure.

Valapoint
Spot Household Spending Leaks
Vala helps couples identify recurring charges, subscriptions, and bill spikes, with tailored insights into spending patterns and potential savings opportunities.

Visit Valapoint

TL;DR

  • There is no single right answer. Regulators describe full merging, a joint account plus individual accounts, and fully separate finances as common options.
  • Start with a shared list of income, debts, credit scores and goals before you open or close any account.
  • If your incomes differ, a proportional split often feels fairer than 50/50.
  • Schedule a short money check-in every month or quarter so nothing builds up quietly.
  • Update beneficiaries and basic legal documents after the wedding.

Table of Contents

Three ways couples combine money

Before you change any accounts, know what the options look like. Fidelity describes three broad models: entirely separate, partially combined and entirely combined. Here is how they play out day to day.

Model How it works Works well when Watch out for
Fully merged All income goes into joint accounts. All bills and spending come from them. You share goals and similar spending habits. One partner feeling they must justify small purchases.
Hybrid (“yours, mine and ours”) A joint account covers bills and shared goals. Each person keeps personal accounts. You want teamwork and some privacy. Agreeing on how much goes into the joint account.
Fully separate Each person keeps their own accounts and pays an agreed share of costs. One partner has large debt or runs a business. Ongoing work to split costs and savings fairly.

NPR describes the hybrid idea as a “theirs, mine and ours” approach, where the joint account handles bills and shared goals and each spouse keeps personal money for discretionary purchases. For many couples it is the easiest place to start, and you can move toward more or less sharing later.

What research says about joint accounts

A study of 230 engaged or newly married couples followed for two years found less money conflict and stronger relationship quality among couples assigned to joint accounts. One of the researchers also noted that a joint account can be paired with attached individual accounts so each partner keeps privacy and autonomy. The study suggests that joint accounts reduced scorekeeping. That is useful, but it does not mean every couple must merge everything.

When separate accounts make sense

Merging is not always the right move. The California Department of Financial Protection and Innovation says separate accounts may be particularly appropriate when one spouse has significant debt, owns a business, has substantially different financial habits, or needs independence for safety. It also lists a history involving mental illness, substance abuse or spending addiction.

If any of those apply, keeping some accounts separate is a sound choice and not a sign of distrust. If you are worried about safety, talk to a qualified professional, such as a domestic violence advocate or an attorney in your state.

Step-by-step: how to combine finances after marriage

Banks and regulators give very similar advice on the order of steps. Here is a plan built from the FDIC’s consumer guidance and a bank’s ten-step guide.

  1. Share the full picture. Talk through income, debts, spending habits, credit scores, savings goals and worries. The FDIC suggests starting with a shared inventory of each partner’s income and expenses.
  2. Review credit reports together. Knowing each other’s credit history now avoids surprises when you apply for a loan or a mortgage.
  3. Choose your structure. Decide whether you will use individual accounts, joint accounts or both, and which account pays recurring bills or holds savings.
  4. Open the accounts you need. You may only need one joint checking account and one joint savings account.
  5. Define shared expenses. Typical examples are housing, utilities, groceries, insurance and transportation.
  6. Decide how each person contributes. More on this below.
  7. Build a household budget. List income, then essentials such as housing, food, insurance and minimum debt payments, then discretionary categories like dining and entertainment.
  8. Set shared goals. An emergency fund, a home down payment, a trip, or paying off debt.
  9. Automate. Set up automatic bill payments and transfers so the plan runs by itself.
  10. Update the paperwork. Review insurance, beneficiaries and credit, and consider wills and powers of attorney.

You do not have to finish all ten in one weekend. Many couples handle steps 1 to 3 in a single relaxed conversation and the rest over a month or two.

How to split bills when you earn different amounts

This is where many couples get stuck. The FDIC gives three workable structures:

  • Combine all income and obligations.
  • Split responsibility by agreed expenses, such as one partner paying rent and the other paying utilities and groceries.
  • Allocate bills and debts by income percentage, for example 60% and 40%.

The California DFPI warns that a 50/50 split can cause problems when incomes differ substantially, and offers proportional contributions as an alternative. U.S. Bank adds that couples should also decide whether to fund the joint account with both full paychecks or fixed monthly amounts.

A worked example

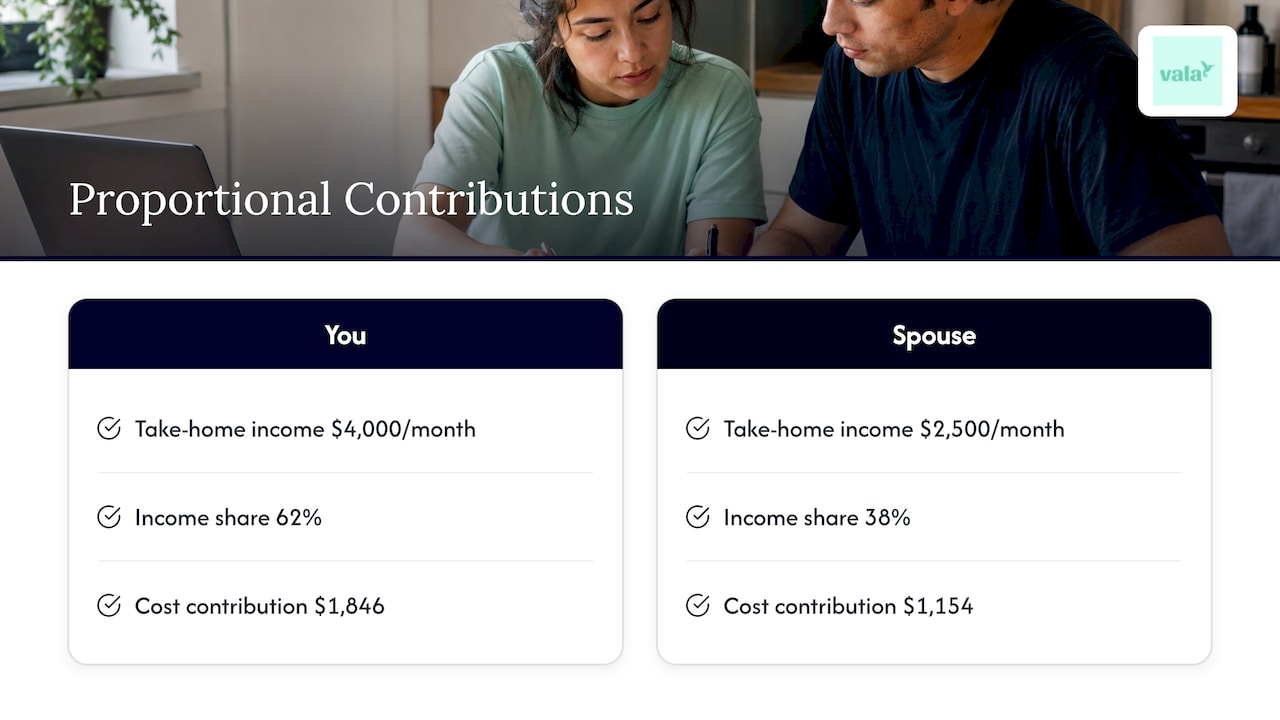
Say your take-home pay is $4,000 a month and your spouse’s is $2,500. Together that is $6,500, so you earn about 62% and your spouse about 38%. If shared costs are $3,000 a month, you would put in about $1,846 and your spouse about $1,154. (These numbers are an illustration, not a recommendation.) What is left stays in each person’s own account for personal spending.

Income shares and proportional monthly cost contributions

If you want to avoid doing this math every month, a split bills app can track who owes what for shared costs.

Deciding what goes in the joint account

A simple rule: the joint account pays for what you both agreed is shared. Everything else is personal.

  • Usually shared: rent or mortgage, utilities, groceries, insurance, transportation, shared subscriptions, savings goals.
  • Usually personal: hobbies, gifts, personal care, nights out with friends, and anything either of you wants to buy without explaining it.

This balance matters. For ideas on how couples keep some spending separate, see why couples keep some spending separate. To understand the mechanics, what a shared budget is and how it works covers common methods.

Also agree on an account floor, a minimum balance you keep in the joint account, and a spending threshold above which you check with each other first. U.S. Bank recommends agreeing on spending categories and an account floor, and, preferably, a separate joint emergency fund in a high-interest savings account.

Handling debt, credit and spending-style differences

Different spending habits are normal. The goal is a plan both of you can live with.

Debt. Be open about every balance, including student loans and credit cards. Decide together who pays what and how existing debts will be addressed. The FDIC lists this as one of the key agreements to reach.

Credit. Getting married does not by itself merge your credit reports, but joint accounts and joint loans link you financially. Review both reports so you know what lenders will see.

Liability for debts. Who is responsible for a debt depends on your state. A Baylor law review explains that marital-property and creditor outcomes vary by state, the type of debt, when it was incurred and each spouse’s involvement. If one of you has significant debt or a business, speak with a family or estate attorney in your state before you merge assets.

Spending style. If one of you is a saver and the other a spender, personal allowances help. Each person has guilt-free money, and the joint account stays on track.

Joint accounts: what to know before you open one

Joint accounts bring transparency, and they also bring shared access. A bank’s guidance on joint accounts notes that holders can generally view transactions, withdraw funds and close the account, so opening one takes a high level of trust. The same source notes that joint access can be useful during an emergency or after a partner’s death.

Practical tips for using a joint account well:

  • Name the purpose of each account, such as bills, savings or travel.
  • Turn on balance and low-funds alerts for both of you.
  • Keep your own emergency cushion in an account only you control if you want extra security.
  • Document how you would divide the account if your situation changed.

Safeguards that keep both of you secure

Merging works best with a few habits built in.

  • Monthly or quarterly check-ins. A bank guide recommends comparing spending with the budget, discussing big upcoming expenses, reviewing savings progress and adjusting the plan. Keep them to 30 minutes and put them on the calendar.
  • An emergency fund. Build it jointly, and aim for a size you both feel comfortable with.
  • Updated beneficiaries and documents. U.S. Bank says that, at minimum, adults should have a will, a healthcare directive and a financial power of attorney, and newly married spouses should update beneficiaries and estate documents. An estate planning attorney can tailor these to your state.
  • Personal spending money. It reduces friction and keeps the joint account focused.

Our perspective

We built Vala around a simple observation: most money tension in a marriage is not about big decisions. It comes from small, recurring things that nobody is watching, like a forgotten subscription, a bill that crept up, or a shared dinner nobody settled.

That is why we think merging finances should start with visibility. When you can both see recurring charges, upcoming bills and shared expenses in one place, the conversation shifts from “who spent that?” to “what do we want to do with this?”

Vala is designed to find hidden money leaks, review recurring subscriptions, remind you about upcoming bills and connect shared expenses to a single budget view. It uses secure bank integration through Plaid. You decide how much to share, so a hybrid setup with joint and personal money works just as well as a fully merged one.

Our advice: do not wait for the perfect system. Pick a structure, automate what you can, and review it together regularly.

SaverStride

Find leaks before you merge

One smart move before you combine accounts is to see what you are both actually paying for. Two people often carry overlapping streaming services, gym memberships and app subscriptions. Merging without a review means you may carry both sets forward.

Vala’s Money Leak Check looks for hidden recurring charges and unexpected bill spikes so you can decide what to keep, cancel or share. Our SaverLite plan is $2.99 per month, and SaverPro is $5.99 per month. You can also start with the Money Leak Check.

Valapoint

If you want to dig in first, try our subscription cost calculator or see how to find hidden recurring charges. Once you are ready to share the budget, our budget app for couples lets you track shared expenses and goals together, and the guide to a budget app for newlyweds covers the first months of married life.

A simple first-month timeline

If the ten steps feel like a lot, here is a way to spread them out.

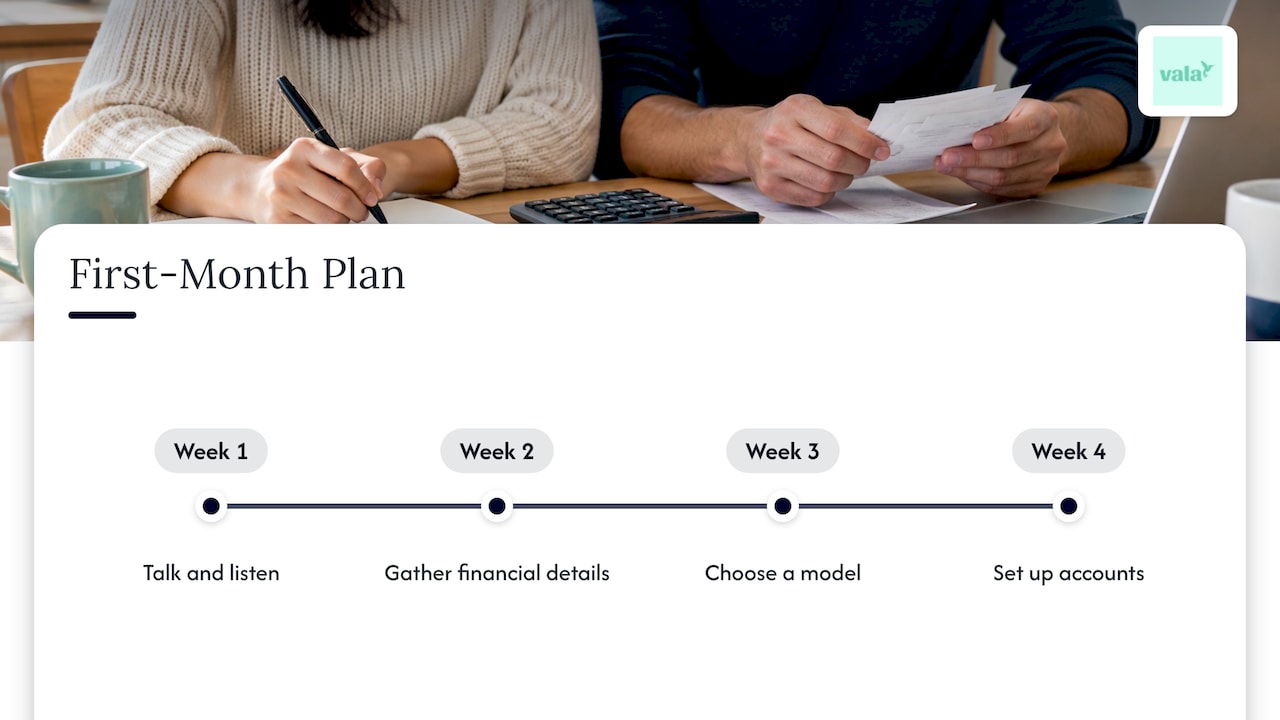
Week 1: Talk. Sit down with coffee, not a spreadsheet. Share income, debts, goals and worries. Agree on nothing yet, just listen.

Week 2: Gather. Pull your statements and list recurring bills and subscriptions. Check credit reports. Decide which expenses are shared.

Week 3: Decide. Choose a model (merged, hybrid or separate) and a contribution method (equal, proportional or by bill). Set personal allowances.

Week 4: Set up. Open any joint accounts, move over the agreed amounts, automate bills and savings transfers, and book your first check-in. Add a reminder to update beneficiaries and look at wills and powers of attorney.

After that, treat the system as adjustable. A raise, a new baby, a move or a job change are all good reasons to revisit your numbers.

A simple first-month timeline

FAQ

Do married couples have to combine their finances?

No. The FDIC encourages couples to discuss whether to use individual accounts, joint accounts or a combination, and to agree on which accounts pay recurring expenses or hold savings. Many couples start with a hybrid setup and adjust over time.

Should I combine finances before or after the wedding?

Talk about money before the wedding, then make account changes when you are both ready. Sharing income, debts and credit scores first means the actual merging is a set of agreed steps instead of a surprise. There is no deadline for opening joint accounts.

What if one of us earns much more?

Consider paying shared costs in proportion to income instead of splitting 50/50. The FDIC gives an example of a 60% and 40% split. Each person then keeps the remainder for personal spending and individual goals.

How often should we review our finances together?

Monthly or quarterly works for most couples. Use the time to compare spending with your budget, look at upcoming large expenses, check savings progress and adjust the plan.

Sources

Bank Fee Refunds: Which Fees You Can Get Back and How

You can often get a bank fee refunded. Overdraft, insufficient funds, monthly maintenance and out-of-network ATM fees are the ones banks reverse most often. A fee charged in error, or one that breaks your account terms or federal rules, is a dispute the bank has to take seriously. A fee that was correctly charged is usually a one-time courtesy you have to ask for. This guide shows you how to tell the difference, what to say, where to escalate, and how to confirm the money actually came back.

Valapoint
Spot Recurring Charges Before They Add Up
Vala identifies subscriptions, recurring charges, and bill spikes, then provides tailored insights to help you manage household spending.

Visit Valapoint

TL;DR

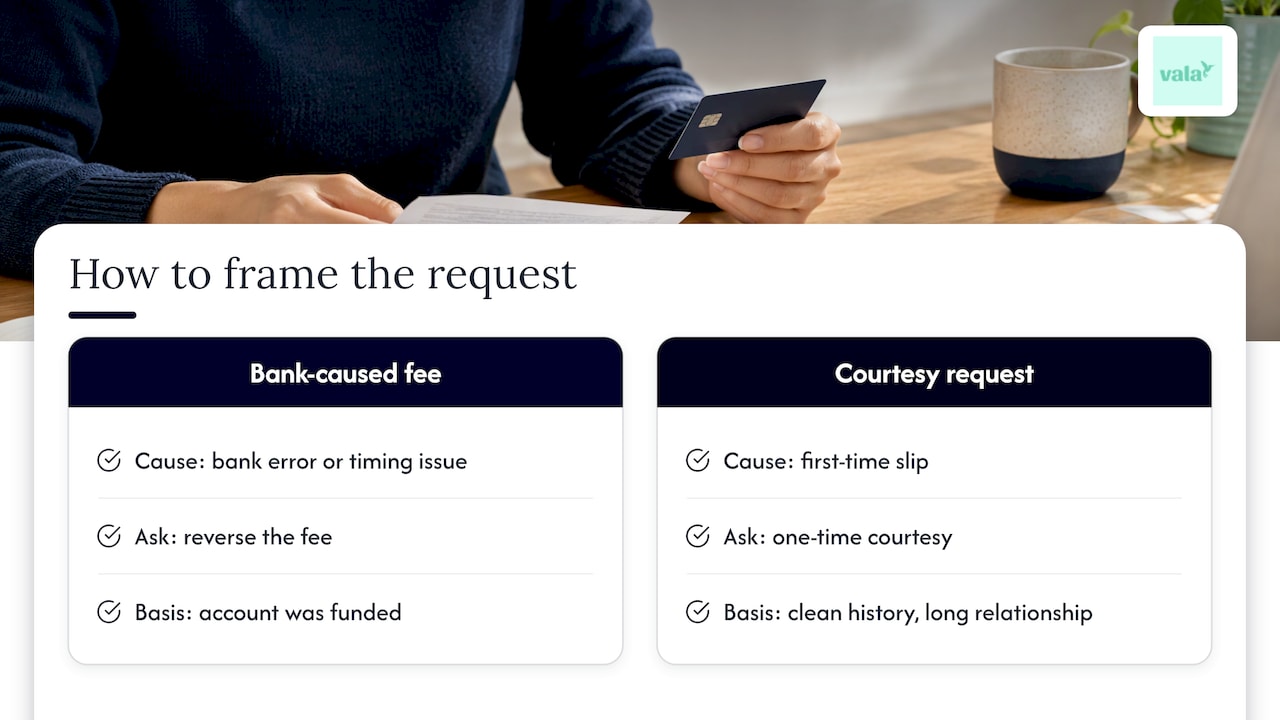
  • Ask for a refund as soon as you spot the fee. Lead with the cause: a bank error, a posting-order problem or a charge that contradicts your account terms. If it was your own slip, ask for a one-time courtesy reversal.
  • Banks cannot charge an overdraft fee on a one-time debit card purchase or ATM withdrawal unless you opted in to overdraft coverage. Checks and recurring payments are different.
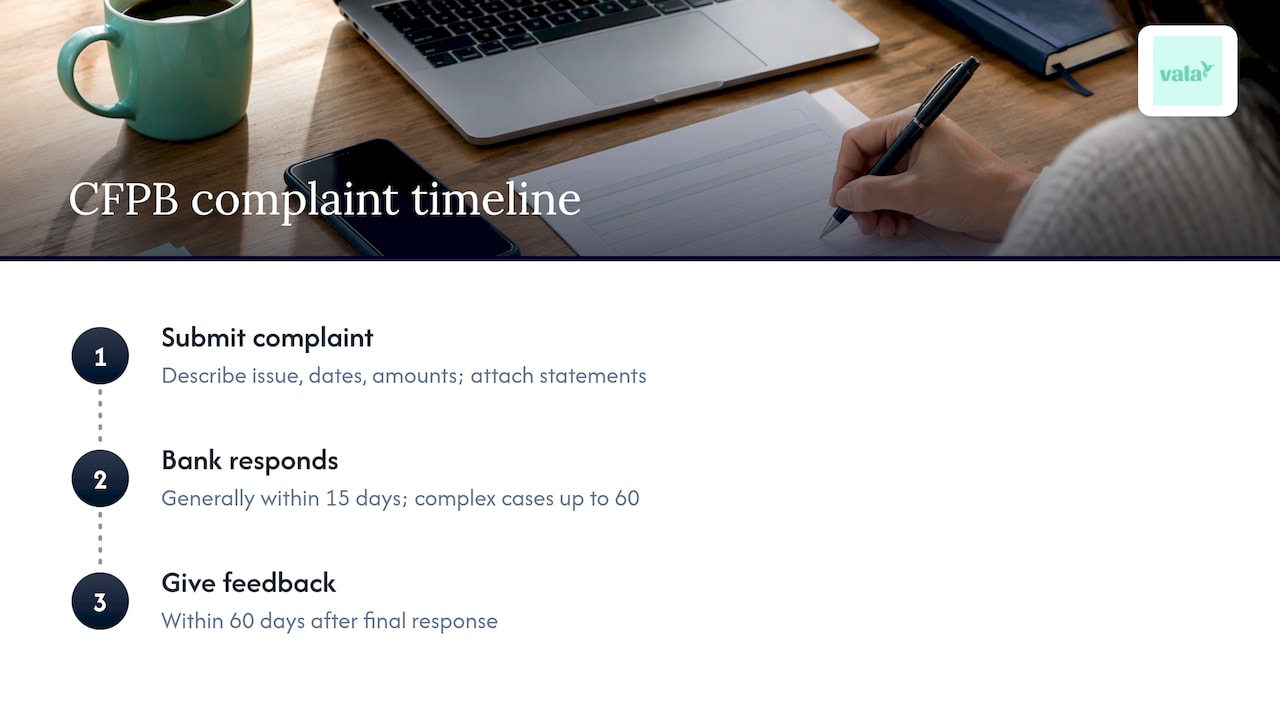
  • If the first agent says no, ask for a supervisor, put the request in writing, then file a complaint with the Consumer Financial Protection Bureau (CFPB).
  • Refunds appear as a separate credit on your statement. Check the label and the date, because some banks post ATM refunds at the end of the statement cycle.
  • The cheapest refund is the fee you never pay. Alerts and a regular review of your charges catch most repeat fees.

Table of Contents

Which bank fees can you ask to have refunded?

Most checking account fees are open to a request. The ones people get reversed most often are:

  • Overdraft fees, charged when you spend more than your balance.
  • Non-sufficient funds (NSF) or returned-item fees, charged when a payment bounces.
  • Monthly maintenance fees, charged when you did not meet the requirements to waive them.
  • Out-of-network ATM fees, charged by your bank or by the ATM owner.
  • Foreign transaction fees, when they were charged in error.
  • Any fee that breaks your bank’s own rules or disclosures.

That list comes from a guide to disputing bank fees. The same guide notes that banks routinely waive a first overdraft, NSF or maintenance fee for customers in good standing.

Courtesy refund versus fee you are owed

This distinction decides how you open the conversation.

A courtesy refund is goodwill. The bank charged the fee correctly under your agreement and chooses to give it back. You have no legal right to it, but a clean history, a long relationship and a first-time slip all help. One consumer-finance explainer puts it plainly: a waiver is goodwill, not a right, while an accounting error is a different matter.

A fee you are owed back is one the bank should not have charged. Examples:

  • The fee is not in your fee schedule.
  • The fee does not match the amount in your account disclosures.
  • A deposit posted late because of the bank, and the fee followed.
  • The bank charged an overdraft fee on a one-time debit card purchase or ATM withdrawal when you never opted in.

The FDIC says banks must disclose any fee tied to a deposit account, and that every deposit-related fee has to appear in the account opening disclosure and fee schedule. If a charge on your statement does not match those documents, you have your evidence.

The overdraft rule that catches many banks

Overdraft fees are the biggest refund category, and one rule works in your favor. The CFPB states that banks cannot charge an overdraft fee on one-time debit card transactions and ATM withdrawals unless you opt in. The same page says banks may still charge overdraft fees on checks and recurring electronic payments even if you never opted in.

So before you call, sort the fee by the kind of payment that triggered it:

What caused the overdraft Can the bank charge an overdraft fee without your opt-in?
One-time debit card purchase No
ATM withdrawal No
Check Yes, it may
Recurring electronic payment (autopay, bill pay) Yes, it may

If the fee was on a coffee, a gas pump or an ATM withdrawal and you do not remember opting in, say so clearly and ask the bank to show you the opt-in record. The CFPB says that if you do not believe you authorized debit overdraft coverage and the bank charged you anyway, you may file a complaint with the CFPB.

The picture has more layers than a simple yes or no. Experian notes that even without opt-in, a bank can still charge a non-sufficient funds fee, and a merchant can charge a returned item fee for declined payments. Read the exact fee name on your statement before you decide which argument fits.

How to ask for a refund, step by step

1. Gather the facts first

Take five minutes before you call. A consumer-finance guide suggests you screenshot the fee’s date, amount and description, read the fee schedule linked in your account disclosures, and note your tenure, direct deposit and whether this was a first or rare event.

Have this on hand:

  • The fee name, amount and date.
  • The transaction that triggered it.
  • How long you have banked there.
  • Any other fees in the same month.

If you want a cleaner view of your own activity first, our guide to reconciling bank transactions walks through matching what the bank posted to what you expected.

2. Call or visit soon after the fee posts

Speed matters. The guide recommends you call within a few days, explain the charge and ask for a one-time courtesy refund. You can also speak to a teller or use in-app chat, and Experian suggests explaining what caused the overdraft, such as a delayed deposit or an automatic payment that cleared earlier than expected. It also notes banks may be more forgiving of long-time customers with a responsible history.

3. Lead with the cause

3. Lead with the cause

The opening line changes the weight of your request. If the cause was a bank error, a timing or posting-order issue, or something that contradicts your account terms, lead with that instead of asking for a favor. That is a dispute, and it carries more weight.

Sample wording for a bank-caused fee:

“I’m calling about a $35 overdraft fee posted on [date]. My paycheck was deposited on [date], before the purchase. I’d like the fee reversed because the account was funded.”

Sample wording for a courtesy request:

“I’ve banked with you for [X] years with direct deposit, and this is the first overdraft fee I can remember. Could you reverse it as a one-time courtesy?”

Keep it short, polite and specific. Ask for the outcome you want, then stop talking.

4. Get the result in writing

Before you hang up, ask when the credit will post and what it will be called. Write down the agent’s name, the date and a reference number. If the agent says a refund is coming, check for it within a few business days.

What if the bank says no?

A first “no” is often just the first agent’s limit. Work up this ladder:

  1. Ask for a supervisor or the retention team. Repeat the cause and your history.
  2. Write it down. Send a message through the bank’s secure inbox or a letter that states the fee, date, amount and reason it should be reversed, cites the rule or disclosure that applies, and sets a reasonable deadline. This is the approach recommended in the dispute guide.
  3. File a CFPB complaint. This is free and can be done online or by phone.

Filing a CFPB complaint

Describe the problem in your own words, include key dates and amounts, and attach statements. The CFPB sends the complaint to the bank, which generally responds within 15 days, or up to 60 days in more complex cases. According to Bankrate, some companies take up to 60 days to give a final response, and you then have 60 days to give feedback in a post-complaint survey.

CFPB complaint response and feedback timeline

A complaint does not guarantee a refund. It does force the bank to formally address your dispute instead of closing it at the customer service level, and complaints go into a public database, so banks tend to treat them with care.

If the fee involved an unauthorized electronic transfer, the timeline is tighter. One source says you typically have 60 days from the date the charge appeared on your statement to dispute it under the rules, so do not wait.

Automatic refunds: what “overdraft fee forgiven” programs look like

Some banks build refunds into the account so you never have to call. These programs have rules, and the details matter. For example, U.S. Bank’s overdraft benefit refunds the overdraft fee if you make a qualifying deposit before 11 p.m. ET on the same day the balance went negative. If the account is overdrawn by $50 or less, no fee is charged. If it is overdrawn by $50.01 or more, the fee is not refunded.

If your bank offers something like this, set a reminder to deposit before the cutoff on any day your balance dips. Check your own bank’s account page for its current terms.

How to track an ATM fee refund

ATM fees come in two parts: the one your bank charges and the surcharge the machine’s owner adds. Some accounts reimburse them automatically. Others only reimburse if you ask.

LegalClarity says the average out-of-network ATM fee is around $3.19, and most banks that reimburse set limits, such as a monthly dollar cap (often near $10 per cycle) or a fixed number of reimbursements per month.

What the refund looks like

The label varies by bank. Here are real examples from bank help pages:

Bank type How it appears When it posts
A large member-based bank “ATM Rebate” on monthly statements, up to $10 per statement cycle Each statement cycle
A community bank “ATM SURCHRG REVERSAL” No later than the second business day
A regional bank Immediate refund of out-of-network fees, with annual caps of up to $250 or $150 depending on the account Right after the ATM transaction posts

More generally, ATM reimbursement credits often appear as a separate line labeled “Fee Rebate” or “ATM Surcharge Refund”. Some banks credit them within a day or two, while others issue one combined credit at the end of the statement cycle. Investopedia notes that in most cases reimbursements are automated, so you do not need to keep receipts or fill out paperwork.

A simple tracking routine

  1. When you pay an ATM fee, note the date and amount in your phone or screenshot the receipt.
  2. Wait for the window your bank states: a couple of business days, or the end of the cycle.
  3. Search your transactions for the refund label and match it to the fee.
  4. If it is missing after the window, contact the bank with the date, amount and ATM location.
  5. Keep track of any monthly cap so you know when you are paying out of pocket.

The same habit works for any refund. When a bank approves an overdraft refund, it shows up as a credit often labeled “Fee Reversal” or “Overdraft Refund”. If your account is negative at the time, the credit reduces or clears that balance once it posts.

Recognize the fee before you chase it

Bank statements use shorthand. Here is what common names usually mean, based on a plain-language fee explainer:

  • Monthly Service Fee: you did not meet the requirements to waive it.
  • Overdraft Fee or OD Fee: you spent more than your balance.
  • NSF Fee: a payment bounced.
  • ATM Fee: you used an out-of-network ATM.
  • Paper Statement Fee: you receive mailed statements.
  • Dormant or Inactivity Fee: the account has not been used.
  • Early Account Closure Fee: you closed the account too soon.
  • Stop Payment Fee: you asked to stop a check or payment.
  • Returned Item Fee: a deposited check bounced.

The FDIC notes that overdraft fees may cost around $35 per transaction, and some banks also charge a continuous overdraft fee every day the account stays overdrawn. A few small fees can add up quickly, so it is worth reviewing your statement line by line.

Stop paying the same fee twice

A refund helps once. A routine helps every month. These steps come from the same fee explainer and from our own guides:

  • Decide whether you want overdraft coverage at all. The fee explainer recommends opting out if you would rather have a purchase declined than pay a fee.
  • Set a low-balance alert around $100 to $150, plus large-transaction and fee-charged alerts.
  • Find your bank’s ATM network before you travel.
  • Switch to e-statements if a paper statement fee applies.
  • Time your autopay and bills so they clear after payday. See how to predict an overdraft before payday and our three quick changes to avoid overdraft fees.
  • Watch for double charges that look like fees. Our guide to detecting duplicate charges fast shows what to look for.

Our perspective: fees are a pattern, not a one-off

We see a bank fee refund as a good first step, and a repeating fee as the signal that matters more. One $35 reversal feels like a win. But when the same type of fee shows up three months in a row, the real problem is timing, a balance that dips before payday, or a recurring charge you forgot about.

That is why we built Vala around money leaks instead of simple expense totals. Our approach is designed to help you spot recurring charges, subscriptions and unexpected bill spikes, connect them to your cash flow, and see what is coming before it lands. Bill reminders and future cash flow simulations are there so the next fee never gets the chance to post.

Our advice: ask for the refund, then use what you learned to close the gap. A fee you have a plan for is a fee you stop paying.

SaverStride

Find the next fee before it finds you

If you want a quick view of where small charges are slipping through, try our Money Leak Check. It looks at your spending for recurring charges, subscriptions and bill spikes, and bank connection runs through Plaid, so your sensitive details stay protected.

Valapoint

Vala is free to start, and paid plans start with SaverLite at $2.99 per month, with SaverPro also available for fuller tools. You can start your free analysis in a few minutes. If you want to see what a recovery plan can look like, read how an app can help with recovering $200 or more in 20 minutes.

FAQ

Can a bank refuse to refund an overdraft fee?

Yes, if the fee was charged correctly under your agreement, a refund is a goodwill decision. Ask again with a supervisor and lead with the cause. If you believe the fee broke your account terms or the opt-in rule for debit card and ATM transactions, put the dispute in writing and file a CFPB complaint.

How long does a bank fee refund take to show up?

It depends on the bank and the fee type. Some ATM refunds post right away or within a couple of business days, while others are combined into one credit at the end of the statement cycle. For a courtesy reversal, ask the agent when it will post and what it will be labeled.

Will asking for a refund hurt my account?

Nothing in the research we reviewed says asking for a fee reversal harms your account. Banks tend to be more forgiving toward long-time customers with a responsible history, so a polite request with your tenure and direct deposit mentioned is a reasonable approach.

Can I get ATM fees refunded?

Some accounts reimburse out-of-network ATM fees automatically, often with a monthly or annual cap. Check your account terms. If your account does not reimburse them, you can still ask for a one-time courtesy refund, and you can plan ahead by finding in-network machines.

Sources

How to Set Up a Fun Money Budget You Can Stick To

A fun money budget is a set amount you can spend on anything you enjoy, with no guilt and no tracking every purchase against your bills. To set one up, cover your needs and savings first, pick a percentage that fits your income (many people start between 5% and 30% of take-home pay, depending on how much room they have), and move that money into its own account or category each payday. Once it’s gone, it’s gone. Once it’s there, you can spend it freely.

This guide shows you what counts as fun money, how to choose your number, how to line up bills with payday so the money is really free, and how to keep dinners, trips and events with friends inside your own limit.

Valapoint
Find Room for Fun Money
Vala helps identify subscriptions, recurring charges and bill spikes that may be taking money away from the things you enjoy.

Explore Vala

TL;DR

  • Fun money is the part of your wants spending that you set aside on purpose and spend without guilt.
  • The CFPB’s 50/30/20 rule gives all wants up to 30% of net income. That is a ceiling for dining, subscriptions and entertainment combined, not a target for fun money alone.
  • Fund fun money right after payday and after bills are covered, so you never borrow from rent to pay for a concert.
  • Check your recurring charges first. Forgotten subscriptions are often the easiest way to free up fun money.
  • With friends, agree on a spending cap before the trip or dinner, and split costs in one shared place.

Table of Contents

What fun money is, and what counts

Fun money is the amount you give yourself permission to spend on things you want but do not need. The Consumer Financial Protection Bureau (CFPB) describes wants as upgrades and extras that are nice to have but not necessary for living, earning income or protecting what you have. Fun money is the portion of those wants you plan for in advance.

The CFPB’s spending tracker gives a useful list of what falls in this bucket: movies or concerts, sporting events and sports fees, books, streaming services and other subscriptions, alcohol, and personal-care items like haircuts. Its monthly household budget worksheet adds cable, pet costs, restaurant meals and coffee to the things people may want.

Not everything on those lists has to be fun money. Here is a simple way to sort it:

  • Needs: rent, utilities, groceries, transportation to work, insurance, minimum debt payments.
  • Savings: emergency fund, retirement, other goals.
  • Fun money: the things you would pick for enjoyment, such as concerts, hobbies, takeout with friends, a new game, a weekend away.
  • Gray areas: a gym membership, a phone upgrade, a haircut. Put these where they fit your life. If a gym membership keeps you healthy and you would never cut it, treat it as a fixed cost. If it is one more thing you rarely use, move it to fun money and decide if it earns its spot.

The point is to define fun by what you enjoy, not by a rulebook. One person’s fun is travel, another’s is books or a hobby. Your budget should say so.

Why a dedicated fun budget works

Most budgets fail because they feel like a list of things you cannot do. A fun money line changes that. You decide ahead of time how much is yours to enjoy, so every purchase inside that limit is already approved.

It also makes the rest of the plan easier to keep. If your wants have a clear home, you are less likely to dip into savings or put dinners on a credit card. The FTC’s consumer.gov budgeting guidance says to list your bills and other expenses, including entertainment, subtract them from your monthly income, and make sure the result is above zero. Fun money is that entertainment line, given a number you choose.

How much fun money should you set aside?

How much fun money should you set aside?

There is no single right amount. The honest answer depends on your income, your bills, your debts and your goals.

Here are the reference points most useful to start from:

Starting point What it means Best for
50/30/20 rule The CFPB presents 50% of net income for needs, 30% for wants and 20% for savings goals A steady paycheck with moderate bills
Fun money as a slice of wants Use part of the 30% for fun money, and keep the rest for dining, subscriptions and extras Anyone who already tracks wants
A smaller flat amount Choose a dollar figure you can afford, even $50 or $100, and raise it as bills drop Students and anyone with tight margins

The CFPB says to choose a rule that fits your financial situation, and Experian makes the same point: the right discretionary amount depends on your income, expenses and financial goals. Lower income or heavier debt payments may call for trimming discretionary spending, and a 50/30/20 split is a starting framework you can customize.

A worked example

Say you take home $3,600 a month. This is an illustration, not a recommendation.

  • Needs at 50%: $1,800
  • Savings at 20%: $720
  • All wants at 30%: $1,080

Out of that $1,080, you might already spend $45 on streaming and apps, $250 on eating out and $120 on gym and personal care. That leaves about $665 you could call fun money, or you might choose to trim the other lines and give yourself more.

Now say rent and loan payments push your needs to 65%. The same math leaves 15% for wants and savings combined. If you take 5% as fun money, that is $180 a month, and you can spend it with a clear conscience because the essentials are covered.

Start with a number you can keep for three months. You can raise it later. It is much harder to cut a number you set too high, because every cut feels like a penalty.

Think in years for big-ticket fun

Some fun spending is lumpy: a trip, a festival ticket, a gift for a friend’s wedding. A $300 monthly travel budget is easier to see as $3,600 a year. Splitting your fun money into a monthly pot for everyday spending and a sinking fund for bigger plans keeps one big purchase from wiping out a month.

Monthly and annual fun money fund comparison

Free up fun money by finding the leaks

Before you cut a category, look for money that disappears without giving you anything. Forgotten subscriptions, free trials that rolled into paid plans, duplicate streaming services and bills that crept up all drain money that could be yours to enjoy.

A quick audit takes about 30 minutes:

  1. Pull up the last two or three months of bank and card statements.
  2. Highlight every charge that repeats.
  3. Mark each one as use weekly, use sometimes or forgot about it.
  4. Cancel the third group today, and set a reminder to review the second group in a month.

Our guides on finding hidden monthly spending leaks and reviewing your monthly finances walk through the process step by step. Even a few canceled subscriptions can turn into a nicer fun money line without touching your savings.

Line up your bills with payday

Fun money only feels free when your bills are already safe. Many people get stuck because rent lands on the 1st and the paycheck arrives on the 5th, so fun money quietly turns into rent money.

The CFPB’s bill due date worksheet suggests a bill calendar. List each bill with its due date, list your paydays, and see where they clash. Then do the following:

  1. Ask for a new due date. Many companies will move a due date to better match your income. The CFPB notes that you do not have a right to choose your date, and some companies may agree as a courtesy while others will not. It is still worth a call.
  2. Set money aside early. If a date cannot move, put aside part of an earlier paycheck for a bill due later in the month, or pay the bill early when you have the money.
  3. Fund fun money last, but on payday. Once the bills due before your next paycheck are covered, transfer your fun money to its own place immediately.

Check your weeks, not just your month

A monthly total can hide a tight week. The CFPB’s cash flow budget maps income and expenses week by week. If the ending balance for a week is negative, you do not have enough to cover that week’s spending. The tool suggests balancing it by cutting wants or renegotiating obligations.

In practice, that means a fun money purchase planned for the week before a big bill is risky, even if the month looks fine. Put big fun spending in the weeks after payday, and keep the weeks before a large bill quiet.

Make the system automatic

Willpower runs out. Habits that run themselves do not. Here is a setup that works for most people:

  • Separate account or card. Move your fun money to a separate checking account, savings account or prepaid card. When the balance hits zero, you stop.
  • Transfer on payday. Schedule it for the day your paycheck lands. A transfer at the end of the month will rarely happen.
  • Weekly or biweekly slices. If you get $200 a month, $50 each week stops you from spending it all on the first weekend.
  • Roll it over, or don’t. Decide in advance. Letting unspent money roll into next month is good for saving up for something bigger. A reset each month is better if you tend to overspend.
  • Review monthly. Ten minutes at month end shows you whether the number was too tight or too loose.

Our monthly budget planner and the guide on automating the 50/30/20 budget give you templates for this.

Keep fun money intact when you split costs with friends

Shared dinners, group trips and event tickets are where fun money gets eaten fastest. The cost is rarely one big purchase. It is a bar tab split in a hurry, a rental house with five people, or a friend who covered tickets and now needs repaying.

A few habits protect your limit:

  • Set a cap before you go. Decide what you can spend on the weekend, and say so early. “I’m in for up to $150” is easier to say before the group books the house than after.
  • Pick one place to track costs. Use a single shared list or app so everyone sees the same totals. Memory and screenshots of receipts lead to awkward conversations.
  • Choose a splitting method that matches the group. An equal split is simple when everyone orders similar things. Itemized splits are fairer when one person skips drinks or an expensive dish. A shared pot, where each person puts in a set amount upfront and one person pays group costs from it, keeps a trip simple.
  • Settle quickly. An unpaid IOU from a friend is a hole in your own budget. Pay what you owe within a day or two, and ask kindly for what is owed to you.
  • Count the full cost. Rides, tips, parking and the coffee before the event all count against your fun money. Include them when you decide whether to say yes.
  • Offer cheaper alternatives. Suggest a potluck, a picnic or a game night when your fun money is low. Good friends usually appreciate the idea.

If your group splits often, a tool that connects shared expenses to your overall budget helps you see what you have left. Our bill splitting and budget planner guide explains what to look for.

Common fun money mistakes

  • Starting too strict. A number so low you break it in week one teaches you nothing. Aim for something you can keep.
  • Counting needs as fun. Groceries are a need. A restaurant dinner is a want. Mixing them hides real spending.
  • Forgetting subscriptions. Streaming, apps and memberships all chip away at the amount you can enjoy. Count them as part of your wants.
  • Paying for fun with credit. If you regularly put outings on a card you cannot pay off, the fun money is not real. Shrink the amount until it is.
  • Never adjusting. Raises, new bills and new goals change your numbers. Review every few months.

Perspective

At Vala, we see the same pattern again and again: people do not overspend on fun because they love spending. They overspend because their money has no clear lines, so fun, bills and savings blur into one balance.

We believe the fastest way to enjoy your money is to see it clearly first. That is why we focus on money leaks. Subscriptions you forgot, recurring charges that crept up and bills that spiked all take from the same pool as your fun money. Find them, and your fun budget grows without anyone telling you to skip the movie.

We also think budgets should look ahead. Knowing which bills are coming and how your cash flow looks over the next weeks makes it easier to say yes to plans without worry. And when friends split dinners and trips, those shared costs belong in the same picture as your own, not in a separate chat thread you check later.

Our tools are designed to make that simple: secure bank connection through Plaid, a clear view of recurring charges, bill reminders and shared expense splitting in one place.

SaverStride

Find the money for your fun budget

If you are not sure where to find room for fun money, start with the leaks. Vala connects securely to your bank through Plaid and reviews your recurring charges, subscriptions and bill spikes, so you can see what you are paying for and what to cancel.

Valapoint

You can run a Money Leak Check to see where your money goes, or try the free Money Leak Calculator for a quick estimate. When you want the full set of tools, such as bill reminders, cash flow planning and shared expense splitting, SaverLite is $2.99 per month. See the plans on the Vala homepage.

FAQ

What is a good percentage for a fun money budget?

There is no single answer. The CFPB presents 30% of net income for all wants as one rule, and says to pick a rule that fits your situation. Fun money is only part of that 30%, so many people give it a smaller share. If your bills or debt payments are heavy, start smaller and raise it as your costs fall.

Should fun money come out before or after bills?

After bills, but on the same day you get paid. Cover the bills due before your next paycheck, then move your fun money into its own account straight away. That way it is protected from rent and utilities, and the rest of your pay is protected from fun.

What if my bills are due before payday?

Try calling the company to ask for a new due date. It is not guaranteed, but some will agree, according to the CFPB. If they will not, set aside money from your earlier paycheck or pay the bill early when you have the funds. A bill calendar makes the gaps easy to spot.

Does fun money include subscriptions?

Usually yes. Streaming, apps and similar memberships are wants, and the CFPB lists them among entertainment spending. Include them in your fun budget, or in the wants total that your fun money comes from. Review them every month, because they are the easiest spending to forget.

How do I keep group costs from blowing my fun money?

Set a cap before you commit, track everything in one shared place and settle up fast. For trips, a shared pot or itemized split often works better than splitting every bill equally on the spot.

Sources

Holiday Gift Budget: How to Set One and Stick to It

A holiday gift budget is one number you can afford, split across the people on your list, with room for wrapping, shipping and surprises. There is no single right amount. The way to find yours is to start with what you have left after essentials, subtract known holiday costs, and divide the rest. This guide walks you through that, step by step, with a worked example and a simple plan for gift exchanges.

Valapoint
Make Room for Holiday Spending
Vala helps identify subscriptions, recurring charges and bill spikes, with tailored spending insights to help you spot potential savings.

Explore Vala

TL;DR

  • Start from what you can afford after rent, utilities, groceries and debt payments, not from what you think you should spend.
  • A common starting point is 1% to 1.5% of annual income, but your own finances decide the real number.
  • Subtract travel, decorations and entertaining first, then divide what is left among recipients, with a firm amount per gift.
  • For friends and coworkers, agree on a group cap and use Secret Santa so everyone buys just one gift.
  • If the numbers don’t fit, shrink the list or change the type of gift. Don’t borrow to cover it.

Table of Contents

Start with what you can afford, not with the list

Most people build a gift list first and add up the cost afterward. That order is how a budget gets blown. Flip it.

The Better Business Bureau suggests you review your income and subtract essentials such as rent, utilities, groceries and debt payments. Then set a clear limit for gifts, travel, parties and other holiday costs. Truist’s guide adds a practical check: look at your checking and savings balances, cash flow and emergency savings along with necessities like rent, utilities and car payments before you decide.

Fidelity puts the rule plainly: your maximum should be money you already have or can save up promptly, not money that would need debt you can’t afford.

Here is a quick way to find that number:

  1. Write down your monthly take-home pay.
  2. Subtract essentials: housing, utilities, groceries, transportation, insurance and minimum debt payments.
  3. Look at what is left across the weeks before the holidays, and decide how much of it can go to the season without touching your emergency savings.
  4. Write that number down. That is your total holiday budget.

If you want a clean view of your monthly numbers first, our monthly budget planner guide shows how to set it up in a few minutes.

How much should you spend on Christmas gifts?

There is no universal amount, and anyone who gives you one is guessing. Still, benchmarks help you check whether your number feels reasonable.

A share of income. Kiplinger’s November 2025 guide suggests 1% to 1.5% of annual income as a starting point, and notes that people with competing goals or a tight season may spend less. Financial planner Jon Lapp, speaking to CNBC, says 1% to 2% of annual income can be reasonable for many households, but the safe amount depends on your individual finances.

How much should you spend on Christmas gifts?

What shoppers nationally plan. Kiplinger also reports National Retail Federation projections of $890.45 per person for holiday items and $627.93 for gifts for family, friends and coworkers. Treat that as context, not a target. Plenty of households spend well under it, and that is fine.

Here is what those percentages look like in dollars. This is simple arithmetic on a sample income, not a recommendation:

Annual income 1% 1.5% 2%
$40,000 $400 $600 $800
$60,000 $600 $900 $1,200
$80,000 $800 $1,200 $1,600

If a figure in that table feels heavy for your month, go lower. A percentage of income says nothing about your rent, your student loans or your savings goals. Your own cash flow wins every time.

Add the costs that aren’t gifts

Gifts are only part of the season. If you leave the rest out, the gift budget quietly absorbs it, and then you overspend.

Kiplinger lists these costs to plan for:

The BBB also recommends planning for transportation, hotels, meals and unexpected expenses. Fidelity suggests you include wrapping and shipping in each person’s allocation so those small costs don’t float outside the plan.

A simple habit: make two lines in your plan. One is “holiday costs,” the other is “gifts.” Fill in holiday costs first, because they are usually known and fixed.

Split the budget among recipients

Once you know the gift total, divide it. Kiplinger’s method is to take your total holiday amount, subtract known costs like travel and decorations, and allocate what remains among recipients.

Some rules that make this easier:

A worked example

Say your total holiday budget is $600, and you know you’ll spend $150 on travel and decorations. That leaves $450 for gifts. One way to divide it:

Line Amount
Partner $100
Two parents, $60 each $120
Two siblings, $40 each $80
Friend exchange and office exchange, $25 each $50
Wrapping and shipping $40
Buffer for surprises $60
Total gifts $450

The buffer matters. It is the line that absorbs the last-minute gift for a neighbor, so the rest of your plan stays intact.

This is only an example. Change the lines to match your list, and the totals to match your own number.

Set a fair budget for a gift exchange

Exchanges with friends or coworkers are where a lot of unplanned spending hides, especially when everyone buys for everyone. The fix is a shared cap and a format where each person buys only one gift.

Kiplinger suggests agreeing on a group cap, such as $25 or $50 per person, and using Secret Santa. Fidelity recommends Secret Santa or White Elephant so each participant buys for one recipient instead of the whole group. Truist recommends discussing limits openly with family or friends, and gives a $25 limit as an example of a proposed cap.

To set the cap without awkwardness:

  1. Ask in the group chat early. A low cap proposed in October feels normal. The same cap in mid-December feels pointed.
  2. Offer two options. For example, “$25 or $40?” lets people pick the lower one without saying why.
  3. Count the cap as the total. Tax, wrapping and shipping come out of the same number. Say so up front.
  4. Pick the format together. Secret Santa for a fixed budget, White Elephant for a more playful swap.

If your group also splits dinners, trips or a shared present, tracking who paid what gets messy fast. Our guide to a budget tracking app for couples and shared expenses covers how to keep group costs clear so nobody is left covering the difference.

Save and stick to the limit while you shop

A plan only helps if it holds at the checkout. These habits come straight from the guidance above:

  • Shop from the list only. Fidelity advises sticking to your list of recipients and amounts, comparing prices and tracking them over time, using coupons, and mailing gifts early to avoid express shipping.
  • Treat the budget as a hard stop. Brian Ford, Truist’s head of financial wellness, frames it this way: once the planned money is gone, shopping stops.
  • Track each purchase the day you make it. A running total is easier to respect than a feeling about how much you’ve spent.
  • Keep a separate pot. If you set aside money in a dedicated savings account ahead of time, the gift budget has a visible edge.

If you shop for new parents, price comparison matters even more, because baby gifts add up quickly. A walkthrough on building a baby registry on a budget can help you see what is actually needed before you buy something extra.

For next year, the easiest way to avoid a December scramble is to save a small amount each month. Our penny saver habits guide shows small daily moves that add up, and a holiday fund of even a modest monthly amount takes the pressure off.

Free up room in your budget before the season

The quickest way to find gift money is often not cutting gifts. It is finding spending you didn’t mean to make. Subscriptions you forgot, recurring charges that crept up and bills that spiked all quietly eat into the money you could use now.

The Truist and BBB guidance both start with checking what you really have. Checking your recurring charges is part of that. A review of the last two or three months often turns up a streaming plan nobody uses, a trial that converted to a paid plan or a fee that rose. Canceling or pausing those can create extra wiggle room before you buy a single present.

You can do this by hand with your bank statements. If you’d like help, our Money Leak Check looks for recurring charges and bill spikes so you can see what is available for your holiday plan.

If your planned spending is more than you can afford

If the numbers don’t add up, you have options that don’t involve guilt or debt.

The BBB says to reduce spending, focus on low-cost or free ways to celebrate, and consider scaling back gift-giving or choosing handmade gifts, acts of service or a family exchange. It also advises that anyone with outstanding debt, especially high-interest debt, prioritize repayment rather than add financial stress.

Consumer-finance expert Erika Rasure told CNBC that gift spending should be intentional and shouldn’t put you in an uncomfortable or dangerous financial situation, such as credit-card debt with no plan to pay it off.

Practical ways to bring the total down:

If you are already carrying card balances, talk with a nonprofit credit counselor before the season starts. They can look at your actual numbers and help you decide how much, if anything, to put toward gifts.

Our perspective

Most holiday budgets fail for a simple reason: the number was never connected to the rest of your money. People pick a figure, and then bills, subscriptions and everyday spending quietly fight it.

We built Vala around that gap. Instead of only recording what you spent, it looks for money leaks, such as subscriptions, recurring charges and unexpected bill spikes, so you can see what is really available. When you know that number, a gift budget stops being a guess.

We also think holiday planning should look ahead. Future cash flow simulations and automated bill reminders help you see how a gift budget fits next to rent, utilities and upcoming payments, before you commit to it. And when friends split dinners, trips or a group present, shared expense tools keep it clear who owes what.

Our advice: set the total first, give every gift a firm amount, keep a small buffer, and check your recurring charges before you shop. Small, steady steps build confidence, and confidence makes the season easier.

SaverStride

Plan your holiday spending with Vala

If you want your holiday gift budget to sit inside a clear picture of your money, Vala can help. Connect your accounts securely through Plaid, review recurring charges, and see what you can safely set aside for gifts. Our Money Leak Check is a good first step, and you can start with the Money Leak Check in a few minutes.

Valapoint

The SaverLite plan is $2.99 per month, and the SaverPro plan adds more. If you’re not sure whether paid features are worth it for you, our guide on free budget apps versus paid ones helps you decide based on what you’d actually save. You can also see how a budget app tracks spending and plans monthly budgets.

FAQ

How much should you spend on Christmas gifts?

There’s no fixed amount. Kiplinger offers 1% to 1.5% of annual income as one starting point, and planners quoted by CNBC say 1% to 2% can work for many households. Your own essentials, debt and savings goals decide the safe number, and it’s fine to go lower.

What’s a reasonable gift exchange budget?

Groups commonly agree on a cap such as $25 or $50 per person, and Kiplinger suggests pairing it with Secret Santa so each person buys one gift. Ask the group for the cap early, and count tax and shipping inside it. Pick the lower number if people are unsure.

What costs should be in a holiday budget besides gifts?

Include travel, entertaining, decorations, wrapping paper, postage, tips and spontaneous purchases. Kiplinger lists these as costs that often get missed. Subtract the known ones first, then divide what remains among your recipients.

What should you do if you can’t afford your gift list?

Shorten the list, lower the larger allocations, or switch to handmade gifts, experiences or a group exchange. The BBB also advises prioritizing debt repayment over adding financial stress. A handwritten card is a perfectly good gift for some people on the list.

When should you start a holiday gift budget?

As early as you can. Starting before the shopping season gives you time to save, compare prices and mail gifts early to avoid express shipping. If you’re starting late, set the total first and fund your highest-priority people first.

Sources

52 Week Savings Challenge: Chart, Math and Easier Variations

The 52 week savings challenge asks you to save $1 in week one, $2 in week two, and add $1 every week until you set aside $52 in week 52. Follow it all the way and you finish the year with $1,378. The idea is simple, the first weeks are almost painless, and the chart below shows exactly where it gets harder so you can plan for it.

This guide covers the standard schedule, a week-by-week chart, the reverse version, a plan for $5,000, what to do when you miss a week, and where to keep the money.

Valapoint
Find Room for Your Savings Goal
Vala highlights subscriptions, recurring charges, and bill spikes that may be getting in the way of your savings challenge.

Explore Vala

TL;DR

  • The standard challenge saves $1 in week 1 up to $52 in week 52, for a total of $1,378.
  • Flipping the order (start at $52, end at $1) gives the same total and front-loads the hard part.
  • A flat $26.50 transfer every week also reaches $1,378 and is the easiest version to automate.
  • The standard schedule will not reach $5,000. That takes about $96.15 a week, or a custom plan.
  • Missing a week is fine. Catch up, skip it, or finish a little lower. Finishing matters more than being perfect.

Table of Contents

How the 52 week money challenge works

You pick a start date, then deposit the number of dollars that matches the week. Week 1 is $1. Week 10 is $10. Week 52 is $52. Add up every deposit from 1 to 52 and you get $1,378.

The appeal is psychological. Early weeks cost less than a coffee, so starting feels easy. By the time the deposits get bigger, you already have a habit and a visible balance. NerdWallet’s walkthrough describes the same schedule, and most of the guides ranking for this topic use it.

The catch is the back half. Weeks 40 to 52 alone add up to $598, which is more than 43% of the whole total. If your budget is tight in December, when holiday spending peaks, that is the stretch to plan for in advance.

52 week challenge chart

You don’t need a fancy printable. A simple table works, and you can copy it into a notes app or spreadsheet. The running total column is the one to watch.

Week Deposit Running total
1 $1 $1
5 $5 $15
10 $10 $55
13 $13 $91
20 $20 $210
26 $26 $351
30 $30 $465
39 $39 $780
45 $45 $1,035
52 $52 $1,378

A few things stand out:

  • You reach $351 by the halfway point, only about a quarter of the total.
  • The last four weeks (49 to 52) add $202.
  • The week-26 deposit is $26, close to the flat $26.50 average, so mid-year is the point where the standard plan starts costing more than an even split would.

How to track it

Log what you actually deposit each week, not what the chart says you should. Mark the week done and keep an eye on the running total. A visual tracker where you check off each deposit makes the progress easy to see, and a spreadsheet with a running-total column does the same job. Both work. Pick the one you will open every Monday.

Three ways to run the challenge

The same $1,378 can arrive in different shapes. Choose the one you are most likely to finish.

Three weekly deposit schedules compared

Standard: $1 up to $52

Easy start, hard finish. Best if your income is steady and you want a quick win to build the habit.

Reverse: $52 down to $1

You start with $52 and drop $1 each week. The total is the same, and NerdWallet notes that the larger early deposits may earn a bit more interest because they sit in the account longer. The bigger benefit is practical: the heavy lifting happens when your motivation is highest, and the holidays get lighter. Neither version is better, and one tracker guide puts it simply: choose the one you are more likely to finish.

Flat: $26.50 every week

If you would rather not think about it, you can automate a $26.50 weekly transfer and land on the same $1,378. This is the version we point most people to, because there is nothing to remember. If you are lining up several recurring payments and transfers at once, a method for organizing your recurring accounts helps keep everything on a calendar.

Here is how they compare:

Version Week 1 Week 52 Total Best for
Standard $1 $52 $1,378 First-time savers who want an easy start
Reverse $52 $1 $1,378 People worried about holiday costs
Flat $26.50 $26.50 $1,378 Anyone who wants it automatic

How to save $5,000 in 52 weeks

The standard challenge tops out at $1,378, so it does not reach a $5,000 goal unless you raise or customize the deposits. You have two options.

Option 1: a flat weekly amount. Divide $5,000 by 52 and you get about $96.15 a week. That is $96.15 times 52 weeks, which lands at $4,999.80, so rounding up to $97 gets you comfortably past the goal. If you already have some money set aside, an initial deposit lowers what you need from future paychecks, and a savings goal calculator lets you test different timelines and deposits.

Option 2: a customized ramp. Clark.com published a $5,000 plan that starts at $20 in week 1, then $35, then $45, and keeps growing. It is heavier in the middle of the year and gets easier in the second half. That works if you expect a raise or a bonus later and want to bank money before then.

No matter which route you pick, check the number against your real income first. If $97 a week would leave you short on rent, a smaller goal you hit beats a bigger one you abandon in March. Bankrate’s guidance is to break a large annual target into regular contributions and to accept that the right amount depends on your income and circumstances.

How to save $5,000 in 52 weeks — overview diagram

What if you miss a week or your income changes?

This is where most challenges quietly die, so plan for it.

  • Missed one week? Tick it off when you catch up, or skip it and accept a slightly lower total. As one chart guide says, the chart is a guide, not a contract.
  • Paid irregularly? The Consumer Financial Protection Bureau says that for seasonal or fluctuating income it may be necessary to temporarily lower automatic savings in months when income comes in under plan. Do that deliberately, then restart.
  • Hit a big bill? Pause the challenge, cover the bill, and resume at your current week. Don’t try to repay every missed dollar in one go.

The same CFPB toolkit notes that the most successful savers set up a system, such as direct deposit, so that saving happens automatically. If your pay lands every other Friday, you can also split each deposit across your paychecks. Our guide to the paycheck budget method shows how to do that for weekly and biweekly pay.

Where to keep the money

The challenge works best when the cash is somewhere you can’t casually spend it. Fidelity lists a checking or savings account, a high-yield savings account, a cash management account, or an investment account as options, and notes that high-yield savings accounts are generally available with FDIC insurance. FDIC insurance covers deposits up to $250,000 per depositor, per insured bank, so a $1,378 balance is well within the limit.

A separate account with its own name (“Emergency fund” or “Trip”) makes it harder to dip into. If you are still deciding what the money is for, our piece on sinking funds versus savings explains how to split goals between short-term bills and a longer cushion.

365 day savings challenge and the $27.39 rule

The 365 day version moves the same idea to daily deposits. There are two common shapes:

  • Flat $1 a day. You set aside $1 every day and finish with $365. It is gentle, but small.
  • Climbing $1 to $365. Day 1 is $1, day 2 is $2, and so on up to $365. Adding 1 through 365 gives $66,795, which is out of reach for most people, so treat this as a novelty rather than a plan.

A more realistic daily goal is what CBS News calls the $27.39 rule: save $27.39 a day for 365 days and you reach $9,997.35, just under $10,000. Round up to $27.40 and you get $10,001. It is a fixed daily amount rather than the $1-to-$52 ramp.

For most budgets, the weekly challenge is easier to maintain. Fewer transactions means fewer chances to forget, and a weekly transfer lines up with how many people get paid.

Our perspective: why challenges stall, and what helps

We like the 52 week challenge because it turns a vague goal (“save more”) into a number you can act on this week. But we see the same pattern when people try it: the plan is not the problem, the money leaking out in the background is.

If $18 a month goes to a subscription you forgot about, $9 to a trial that rolled into a paid plan, and a utility bill jumped last quarter without you noticing, that is real money. Over a year, those small recurring charges can easily cover the larger deposits in the second half of the challenge. So before you start, we suggest reviewing what is already leaving your account. Free up the room first, then set the weekly amount.

We also think automation beats willpower. A transfer that moves on payday does not rely on remembering, and bill reminders help you avoid late fees that would pull money back out. Pair the challenge with paying yourself first and the savings stop competing with everything else for what is left at the end of the month.

Finally, shared goals work better with friends. If you are splitting trips, dinners or events, keeping those costs separate from your challenge money means the savings do not quietly cover someone else’s share.

— SaverStride

Find the money before you start

The biggest barrier to a 52 week challenge is finding the $40 to $50 a week it asks for in the last months. Vala’s Money Leak Check scans your linked accounts through secure Plaid bank integration, flags subscriptions, recurring charges and bill spikes, and shows you what you could redirect to savings. You can begin with the free money leak calculator, or start your free analysis to see your own numbers.

Valapoint

Paid plans start with SaverLite at $2.99 per month, which adds ongoing tools like savings goal management and bill reminders. You can see the full set of features on our finance app page.

Tips to finish all 52 weeks

  1. Start when it suits you. January is popular, but any Monday works. Starting in the fall puts the biggest deposits around summer instead of the holidays.
  2. Automate what you can. Set up a recurring transfer for the flat version, or schedule each week’s amount in advance. Our guide on automating personal savings goals walks through the setup.
  3. Name the goal. A trip, a car repair fund, or a three-month cushion is easier to protect than “savings.”
  4. Plan the spending week too. A weekly spending plan shows you how much is left after bills, so you can see whether this week’s deposit fits.
  5. Build in a buffer. Deposit a few extra dollars in the easy weeks to cushion the heavy ones.
  6. Celebrate milestones. Hitting $351 at week 26 or $1,035 at week 45 is worth noticing. Treat it as progress, not a license to spend it.

FAQ

How much money can you save with the 52 week challenge?

The standard schedule gives you $1,378 after 52 weeks. You deposit $1 in week one and increase by $1 each week to $52 in the final week. If you want a different total, you can scale the amounts up or down.

How do you save $5,000 in 52 weeks?

You need about $96.15 a week, which is a flat plan rather than the $1-to-$52 ramp. You can also use a customized schedule that starts higher and grows. Check that the weekly amount fits your income before committing.

What is the $27.39 rule?

It is a daily savings goal: put away $27.39 every day for 365 days and you finish just short of $10,000, at $9,997.35. Saving $27.40 daily gets you $10,001. It is a different approach from the 52 week challenge, with a larger goal and a daily rhythm.

What if I miss a week?

Catch up when you can, or skip it and finish with a slightly lower total. The goal is a savings habit, not a perfect record. If the missed weeks keep piling up, lower the amounts or switch to the flat plan.

Is the reverse 52 week challenge better?

Not necessarily. It has the same $1,378 total, but you save the bigger amounts first, which can help if you expect expensive holidays. The better version is the one you are more likely to finish.

Sources

Round-Up Savings: How It Works and Whether It’s Worth It

Round-up savings rounds each eligible purchase up to the next dollar and moves the difference into a savings account. Buy a $4.35 coffee and 65 cents goes to savings. You do nothing after setup. It’s worth it for most people as a starter habit, as long as you know what it will and won’t do. On its own it adds up slowly, and it can cause overdrafts if your checking account runs thin.

Below you’ll find how it works, what the numbers look like, what to check before you turn it on, and how to pair it with savings that grow faster.

Valapoint
Find More Room in Your Budget
Vala helps identify recurring charges and bill spikes, so you can see potential savings opportunities beyond spare change.

Visit Valapoint

TL;DR

  • Round-ups take the spare change from debit card purchases and move it into savings automatically.
  • Typical amounts are small. One published estimate puts 50-cent average round-ups at about $276 a year.
  • Federal research found that round-type rules save often but tend to build less than fixed, guaranteed transfers.
  • Check fees, daily transfer timing and your checking balance first, because transfers can trigger overdraft fees if your account runs low.
  • Use round-ups as one layer, alongside a fixed weekly or paycheck transfer and a cleanup of recurring charges.

Table of Contents

What round-up savings means

The idea is simple. Your bank or app watches your eligible debit card purchases, rounds each one up to the nearest dollar, and moves the difference into a savings account. The Consumer Financial Protection Bureau describes it as rounding purchases to the nearest dollar and saving the difference, which adds to your savings without manual effort.

Here is a quick example of one day:

Purchase Rounded to Moved to savings
$4.35 coffee $5.00 $0.65
$12.80 lunch $13.00 $0.20
$37.42 groceries $38.00 $0.58
$9.99 streaming add-on $10.00 $0.01
Day total $1.44

No single transfer feels like anything. That’s the appeal. It works like a digital change jar, and you never have to decide to save.

Some versions round to the nearest dollar only. Others let you multiply the round-up (for example, double it) or round to a larger step like $5. Which options you get depends on the provider.

How much can round-ups really add up to?

How much can round-ups really add up to? — overview diagram

Short answer: less than most ads suggest, but more than nothing.

One media estimate from GOBankingRates used 45.6 payment transactions a month and a 50-cent average round-up to reach about $276 saved in a year. Your number depends on three things:

  1. How often you use your debit card. More swipes means more round-ups. If you pay mostly by credit card, cash or bank transfer, you’ll round up very little.
  2. The average cents lost per purchase. Over many purchases the average tends toward 50 cents, but it can differ if you buy lots of exact-dollar items.
  3. Multipliers and minimums. Doubling or tripling round-ups speeds things up, but it also pulls more from checking.

A simple worked example, which is our own illustration and not a study: 60 debit purchases a month at a 50-cent average is $30 a month, or $360 a year. Double the round-up and it’s $720. Neither is life-changing, but both cover a real expense, like a car registration or a flight home.

What federal research says

The CFPB looked at the outcomes of savings app users in a 2022 report on one savings app’s strategies. In it, rules that trigger depending on your spending (called contingent rules) averaged $1.40 per transaction and 58 triggers a month. The report found that guaranteed rules, meaning fixed transfers that happen no matter what, were associated with more savings building up. The CFPB also noted that contingent rules like round-ups make it easy to save often, yet are linked with lower total savings than guaranteed ones.

CFPB findings on round-up and fixed savings

The takeaway: round-ups are great for building the habit. They’re not the fastest way to build a balance. Pair them with a fixed transfer, and you get both.

Who offers round-ups

You have a few places to look, described here by type:

  • Banks and credit unions. Some offer a built-in round-up feature tied to your checking account. One example is a regional bank whose Round Up Savings program rounds each debit card transaction up and deposits the total into a savings account you choose, with transfers aggregated at the end of each processing day. Check your own bank’s app or website, since availability varies by institution.
  • Savings and budgeting apps. Many apps link to your bank account and let you set round-up rules, then move money into a savings account or a goal.
  • Investing apps. Some round-up tools invest your spare change instead of saving it. That’s a different decision, with market risk, so treat it separately.
  • DIY. You can round up on your own by logging purchases and transferring the difference weekly. It’s free, but it relies on willpower, which is what automation is meant to replace.

What to check before choosing

Before you pick one, run through these questions:

  • Which accounts does it need? Some bank programs require a checking account, a debit card and a separate savings account at the same bank.
  • Which purchases count? Often only debit card purchases are eligible. Credit card, bill pay and transfers may be excluded.
  • Is there a monthly fee? A fee of a few dollars can eat a large share of a small round-up balance. If you’d save $30 a month, a $3 fee takes 10% of it.
  • When do transfers happen? Daily, weekly or when a threshold is reached.
  • Where does the money go? A savings account that earns interest and is covered by deposit insurance is a good place for an emergency fund.
  • Can you cap or pause it? You should be able to set a limit or switch it off in a tight month.

Set it up in five steps

  1. Pick your destination. A separate savings account works best, because out of sight helps. Choose one with no monthly fee, and look at the interest rate.
  2. Check your checking buffer. Look at your lowest balance over the last three months. If you often dip close to zero, build a cushion before you start.
  3. Turn on round-ups. Find the feature in your bank or app. Start with the standard round-up, not a multiplier.
  4. Set a goal. Name what the money is for: a $500 starter emergency fund, a trip, or a security deposit. A target keeps you going.
  5. Review after 30 days. Check how much moved, whether any overdraft or fee hit, and whether you can raise the multiplier.

Fees and overdraft risks to watch

The biggest risk with round-ups is not the feature itself. It’s small transfers leaving a checking account that has little in it. The CFPB advises that when you set up recurring transfers, you should monitor your online account because insufficient funds may lead to overdraft fees.

To stay safe:

  • Keep a buffer in checking, even $100 to $200, before you turn on a multiplier.
  • Watch the days right before payday, when balances are lowest.
  • Ask your bank whether round-ups can overdraw the account, and what happens if they would.
  • Turn on low-balance alerts.

If overdrafts are already a worry, read our guides on predicting an overdraft before payday and avoiding overdraft fees with three quick changes first. Then start round-ups once your balance is steady.

When round-ups make sense, and when they don’t

They fit well if you:

  • Use a debit card for most daily spending.
  • Have never kept up a savings habit and want a painless start.
  • Want to save for a small, specific goal.
  • Split costs with friends and make many small purchases.

They fit poorly if you:

  • Pay mostly with credit cards, so few purchases qualify.
  • Run a checking balance close to zero.
  • Carry high-interest debt. Paying that down usually beats earning savings interest, so put the extra there.
  • Need to build a large amount quickly. Round-ups alone won’t get you there.

The honest limit: round-ups feel like progress because they’re painless, but the dollars are small. If your goal is $3,000 in a year, that’s $250 a month. Spare change won’t do it alone.

Perspective: where we see the real money

We built Vala around a simple observation. For most households, the biggest savings aren’t hiding in coffee change. They’re in recurring charges, subscriptions you forgot, and bills that crept up. Round-ups are a good habit starter, and we like them for that. But a $1.40 transfer can’t compete with a $15 monthly subscription you no longer use.

So our advice is to work from both ends. Let small automatic transfers build the habit. Then look at the leaks that cost you the same amount every month, because stopping one frees up money without any effort at all. When you connect your bank through Plaid, Vala flags recurring charges and sudden bill spikes, so you can see which ones are worth cutting. Then you can send that freed money into a goal on purpose.

If you want to go deeper on automation, our guide to automating personal savings goals and our post on saving automatically with AI insights walk through it step by step.

— SaverStride

Build a savings habit beyond spare change

Round-ups work best as one layer. Here’s how to stack the others.

Add a fixed transfer

Because the CFPB found guaranteed saving rules tied to higher accumulation, set a fixed amount to move on payday. Even $10 or $20 per paycheck works. Increase it when you get a raise.

Cancel what you don’t use

Go through your last three months of statements and list every recurring charge. Cancel the ones you haven’t used in 60 days. Redirect that exact amount into savings, so the saving is automatic. A cancelled $12 subscription is $144 a year, which is more than a lot of people collect in round-ups.

Use small daily choices

Small habits add up too. Our page on penny saver habits that work covers daily moves you can combine with automation.

Keep it all visible

Automation can hide your progress. Check your savings balance once a month and look at the total, not just the transfers. If you’re comfortable connecting accounts, review our five-minute security checklist for budgeting apps first so you know what to look for.

Find your leaks with Vala

If you want to see where your spare dollars are going before you set up round-ups, start with our Money Leak Check. It looks at your subscriptions, recurring charges and bill spikes and shows you what you could recover. Our SaverLite plan is $2.99 per month, and you can see current plan details on the Vala site.

FAQ

Is round-up savings worth it?

For most people, yes, as a first step. It builds a habit with no effort, and a typical estimate of about $276 a year is real money. It’s not enough alone for big goals, so pair it with a fixed transfer.

Do any banks offer round-up savings?

Some do. Certain banks and credit unions have round-up programs that move the difference from debit card purchases into a savings account. Programs and requirements vary, so check your bank’s app or ask a representative about eligibility, fees and transfer timing.

Can round-ups cause overdraft fees?

They can if your checking account runs low, because the transfers still leave the account. The CFPB advises watching your account when you set up recurring transfers. Keep a small buffer and turn on low-balance alerts.

How is a round-up different from a fixed transfer?

A round-up depends on how much you spend, so the amount changes. A fixed transfer moves the same amount on a schedule. Federal research linked guaranteed rules to higher savings, and round-ups to frequent but smaller saving.

Sources